Podcast
“Markets Reward Patience, Not Panic”: Kalpen Parekh on What Drives Wealth Creation
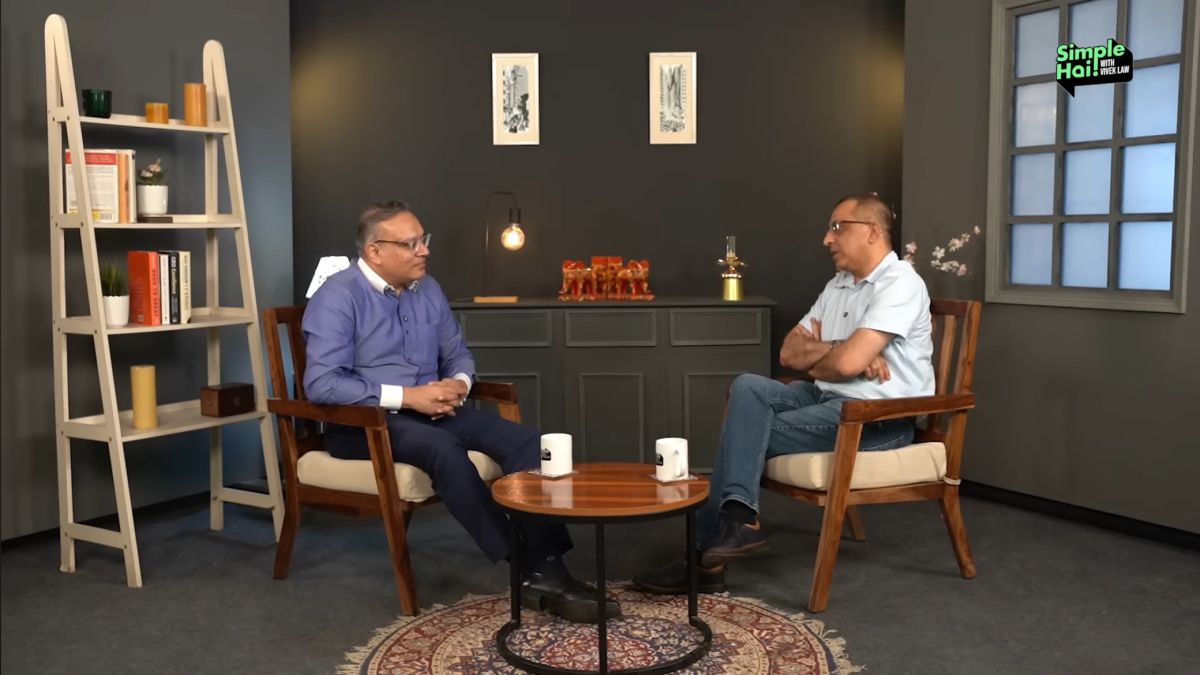
In a candid conversation on the Simple Hai! with Vivek Law podcast, Kalpen Parekh, MD & CEO of DSP Mutual Fund, shared his reflections on investing, market cycles, human psychology, and his own professional journey. Speaking with veteran finance journalist Vivek Law, Parekh emphasised that while the tools of investing are available to all, the discipline to use them well is still rare.
“Instinctive investing is bad investing,” he said. “Most people buy when prices rise out of fear of missing out, and sell when prices fall out of fear. That’s the exact opposite of what good investing requires.”
Parekh told Law that despite years of consistent messaging around patience and long term investing, many investors still stop their SIPs when markets decline. Data, he said, showed that SIP stoppage ratios had crossed 100 in weak markets, evidence of how behaviour continues to undermine returns.
Fighting Evolution to Become a Better Investor
Parekh said he believed that the problem lay deeper than poor financial education. According to him, human brains were wired for survival, not markets. “Our ancestors survived by running from danger. But in markets, you’re often rewarded for doing nothing. It’s anti evolutionary,” he explained.
He told Law that while markets were cyclical, most people approached them as if they were linear. There was a tendency to believe that good times would last forever and that bad phases happened to others. The challenge for investors, he said, was to consciously override these mental defaults.
He pointed out that there were only three things investors could control: how much they saved, where they put that money, and how long they left it untouched. Everything else, market movements, returns, even economic policy, was outside their control.
A Personal Journey Driven by Luck and Learning
Parekh also spoke about his own unconventional journey into financial services. Trained as an engineer, he chose not to pursue it as a career. Instead, he did an MBA in Mumbai in the late 1990s, a time when it was fashionable to do so, and soon found himself working with L&T Finance in money markets.
Parekh credited much of his growth to luck and the quality of people around him, bosses, colleagues, and juniors who taught him important lessons. One boss, early in his career, had advised him to “grow your EPS” and let the market decide your PE. Translated, the advice was simple: be valuable and useful, and the world would eventually reward you.
Why Most Investors Don’t Create Wealth
Despite the strong historical performance of mutual funds in India, Parekh pointed out that very few investors actually benefited. Citing the example of a fund launched in 1997 that grew its NAV over 100 times in 28 years, he revealed that only 23 investors out of 7 to 8 lakh stayed for the entire duration.
“Investing should be like a marriage, not a flirtation,” he told Law. “Too many people exit when things get tough, and re enter when it feels easy again.”
Parekh acknowledged that India had the right conditions for equity investing, a democratic, entrepreneurial and meritocratic society, but cautioned against assuming that high returns were guaranteed. In countries like Japan, he said, long term equity returns had been negligible for decades.
He stressed that people often made the mistake of investing in asset classes after they had already performed well. “A good fund bought at the wrong price can still be a bad investment,” he said. “And a bad asset class bought at the right price can turn out to be great.”
Multi Asset Funds: A Simple Solution for Complex Behaviour
To counter these behavioural pitfalls, Parekh recommended multi asset allocation funds, especially for investors without the guidance of an advisor. These funds, he explained, automatically diversify across equity, bonds, and gold, offering both growth potential and downside protection.
He told Law that gold acted as a kind of “magical joker,” often performing when equity underperformed. While multi asset funds might deliver slightly lower returns than the best performing asset class in any given year, they did so with much less fluctuation, allowing investors to stay the course longer.
He also offered a simple framework based on his 27 years of experience:
In bullish or expensive markets, invest in multi asset funds for built in discipline.
In cheap markets, especially after steep corrections, invest in equities for higher potential returns.
This two line rule, he said, had worked well across market cycles globally.
Focus on Behaviour, Not Just Strategy
Parekh believed that the real question investors should be asking was not “where to invest,” but “how to become a good investor.” He drew parallels with other professions: just as one wouldn’t rely on a friend or a search engine for medical advice, one shouldn’t invest without professional guidance if they lacked expertise.
For those still inclined to go it alone, multi asset funds offered a balanced first step. “They do the heavy lifting of discipline for you,” he said.
Ultimately, Parekh argued, wealth was created either by running a successful business or owning one. For most people, the second option, investing, was simpler. But the catch lay in execution. “It’s not a knowledge game,” he said. “It’s a behaviour game.”
Loving the Journey
Despite the pressures of the market and the cycles of boom and bust, Parekh said he continued to find joy in his work. “It’s intellectually stimulating, it’s purposeful, and it helps people solve real life problems about money,” he told Law. “It doesn’t feel like work, it feels like life.”
After 27 years in the industry, his belief remained unchanged: good investing was simple in theory, hard in practice, and deeply rewarding for those who got it right.
Podcast
Gold Loans, MSME Credit and Digital Lending: Rakesh Singh on India’s Changing Borrowing Habits
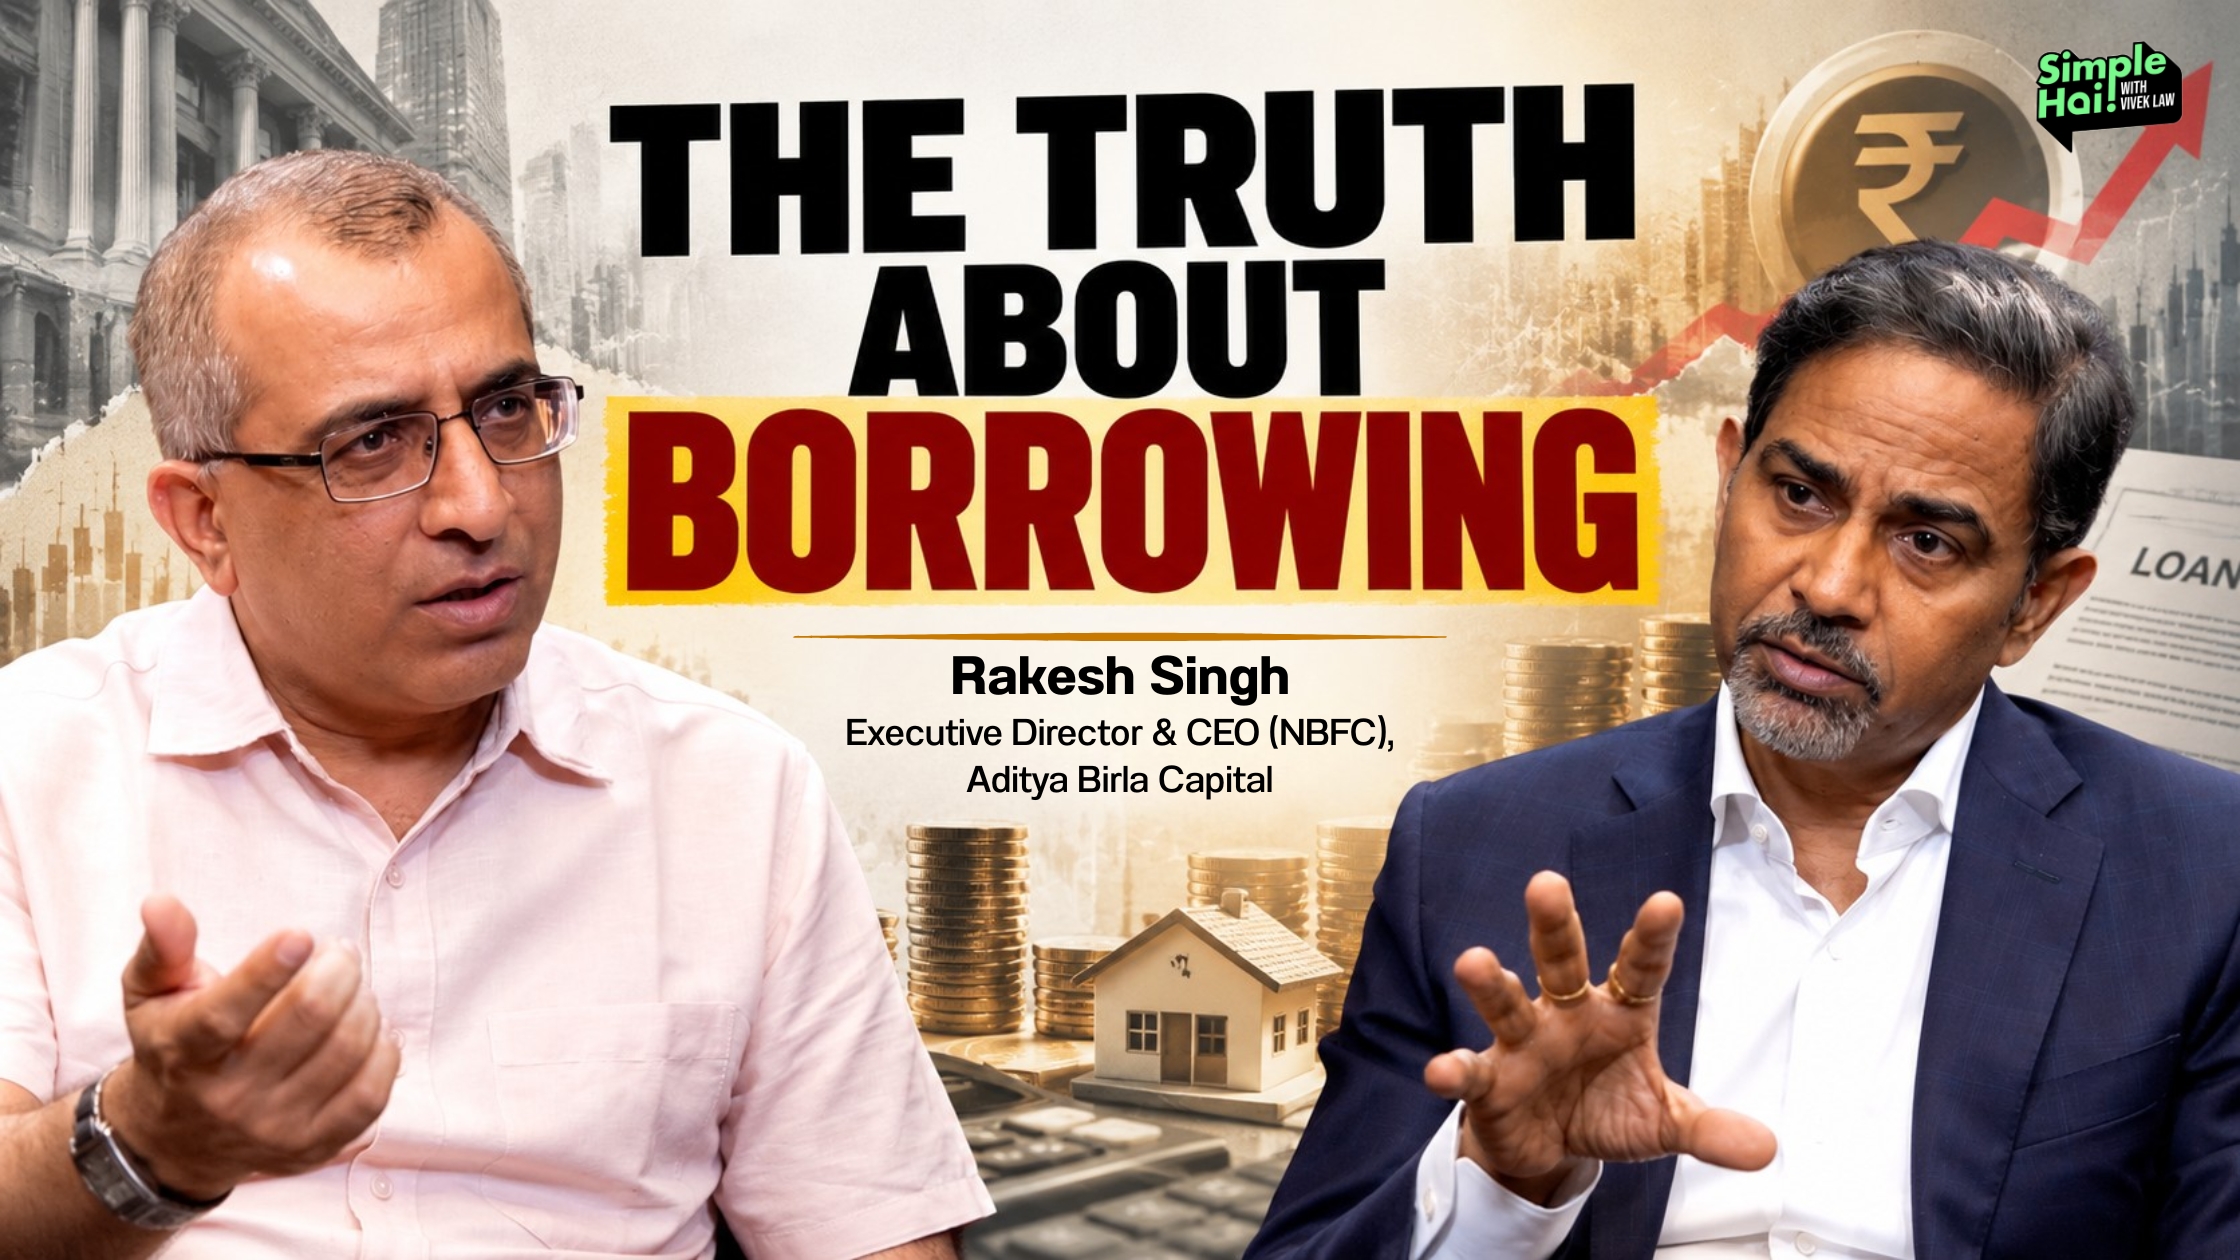
India’s lending landscape is evolving as technology makes credit more accessible and businesses look for faster ways to raise funds. From households using gold as collateral to small businesses seeking formal credit, borrowing is becoming an important part of how individuals and enterprises manage their financial needs.
In a conversation with Vivek Law on The Simple Hai! Show, Rakesh Singh, Executive Director and CEO (NBFC) at Aditya Birla Capital, discussed the growth of gold loans, the credit gap faced by micro, small and medium enterprises (MSMEs), the role of digital platforms in lending, and why responsible borrowing must remain a priority.
Gold Loans: Putting Household Savings to Productive Use
Gold has traditionally been an important form of savings for Indian households. Singh noted that Indian families collectively hold an estimated $5 trillion worth of gold, presenting a significant opportunity for the gold loan market.
According to Singh, the gold loan industry has grown considerably over the past two to three years, partly because rising gold prices have increased the value of the collateral borrowers can offer. He cited an industry size of around ₹19 lakh crore, with NBFCs accounting for approximately ₹4 lakh crore and banks making up the remainder.
Gold loans can help people access funds without selling family jewellery. Singh explained that borrowers often use these loans to invest in their businesses or pay for their children’s education, making them a source of funds for specific financial needs rather than everyday consumption.
He also highlighted the potential in semi-urban and rural areas, as well as Tier 3 and Tier 4 markets, where access to such lending products can expand further.
Trust Is Key to the Gold Loan Business
Borrowing against gold involves more than a financial transaction. For many families, jewellery carries emotional and generational value, making trust an essential part of the process.
Singh said established brands can help customers feel more confident about pledging their gold. Transparency, responsible handling of jewellery and a customer-first approach are important to building that confidence.
He also pointed to a geographical shift in the market. While gold lending was previously concentrated in southern states, Singh said growth is increasingly visible in northern, eastern and central India, including markets such as Delhi-NCR, Uttar Pradesh and Rajasthan.
For Aditya Birla Capital, entering this segment is an opportunity to expand its lending presence across the country while focusing on customer trust and responsible growth.
MSMEs Continue to Face a Credit Gap
Access to formal credit remains a challenge for many small businesses. Singh observed that some MSMEs continue to borrow from friends, family or local sources, sometimes at significantly higher rates, because they cannot easily access suitable formal financing.
He said banks, NBFCs and fintech companies each have a role to play in addressing this gap. Rather than simply competing with one another, these institutions need to reach different customer segments and offer products suited to their requirements.
Speed is another important factor. For a small business, delays in accessing funds can affect day-to-day operations and growth plans. Lenders therefore need to combine appropriate credit assessment with efficient processes.
Singh also shared that approximately 57–58% of Aditya Birla Capital’s loan book, which he referred to as around ₹1.70 lakh crore during the discussion, was directed towards MSMEs.
How Digital Platforms Are Changing Lending
Digital infrastructure is making it easier for lenders to assess small businesses that may previously have had limited access to formal credit.
Singh highlighted the role of digital payments, Aadhaar-based verification, PAN linkages, GST records and credit bureau information in helping lenders understand customers and their financial activity. As more businesses use digital payment systems, lenders can gain a clearer picture of their transactions and banking behaviour.
Aditya Birla Capital developed its Udyog Plus digital platform to serve MSMEs. Singh said the platform had close to 2.4 million registered businesses at the time of the conversation.
Through digital processes, some smaller loans can be assessed, approved and disbursed within minutes. Larger or more complex applications may still require intervention from branches and credit managers.
Digital platforms can also help businesses access services beyond financing, including support related to accounting and human resources.
Digital Lending Must Be Matched With Responsible Borrowing
Technology has made it easier for customers to access credit, including through digital platforms and financing options offered during online purchases. However, Singh cautioned that easier access to loans also brings risks.
When customers take multiple loans from different lenders, their overall debt burden can rise. Singh stressed that lenders need to monitor a borrower’s leverage not just when approving a loan, but also after the money has been disbursed.
For borrowers, understanding repayment capacity is equally important. People should assess how much they can repay, when their income is likely to arrive and whether the repayment schedule suits their financial circumstances. This can be particularly important for those with irregular or seasonal earnings.
Singh also emphasised the importance of awareness around credit scores and repayment discipline. Delayed payments can affect a borrower’s credit record and future access to loans.
The Future of Lending Depends on Access and Awareness
India’s growing economy, expanding digital infrastructure and changing borrowing needs are creating opportunities for lenders. Gold loans can help households unlock funds against an existing asset, while better access to formal credit can support small businesses.
But greater access alone is not enough. As Singh explained, lenders must understand the customer segments they serve, manage risks carefully and ensure that credit reaches borrowers whose needs and repayment capacity align with the product.
For borrowers, the message is equally clear: a loan should serve a financial purpose, and taking one should always involve a clear understanding of its cost and repayment obligations.
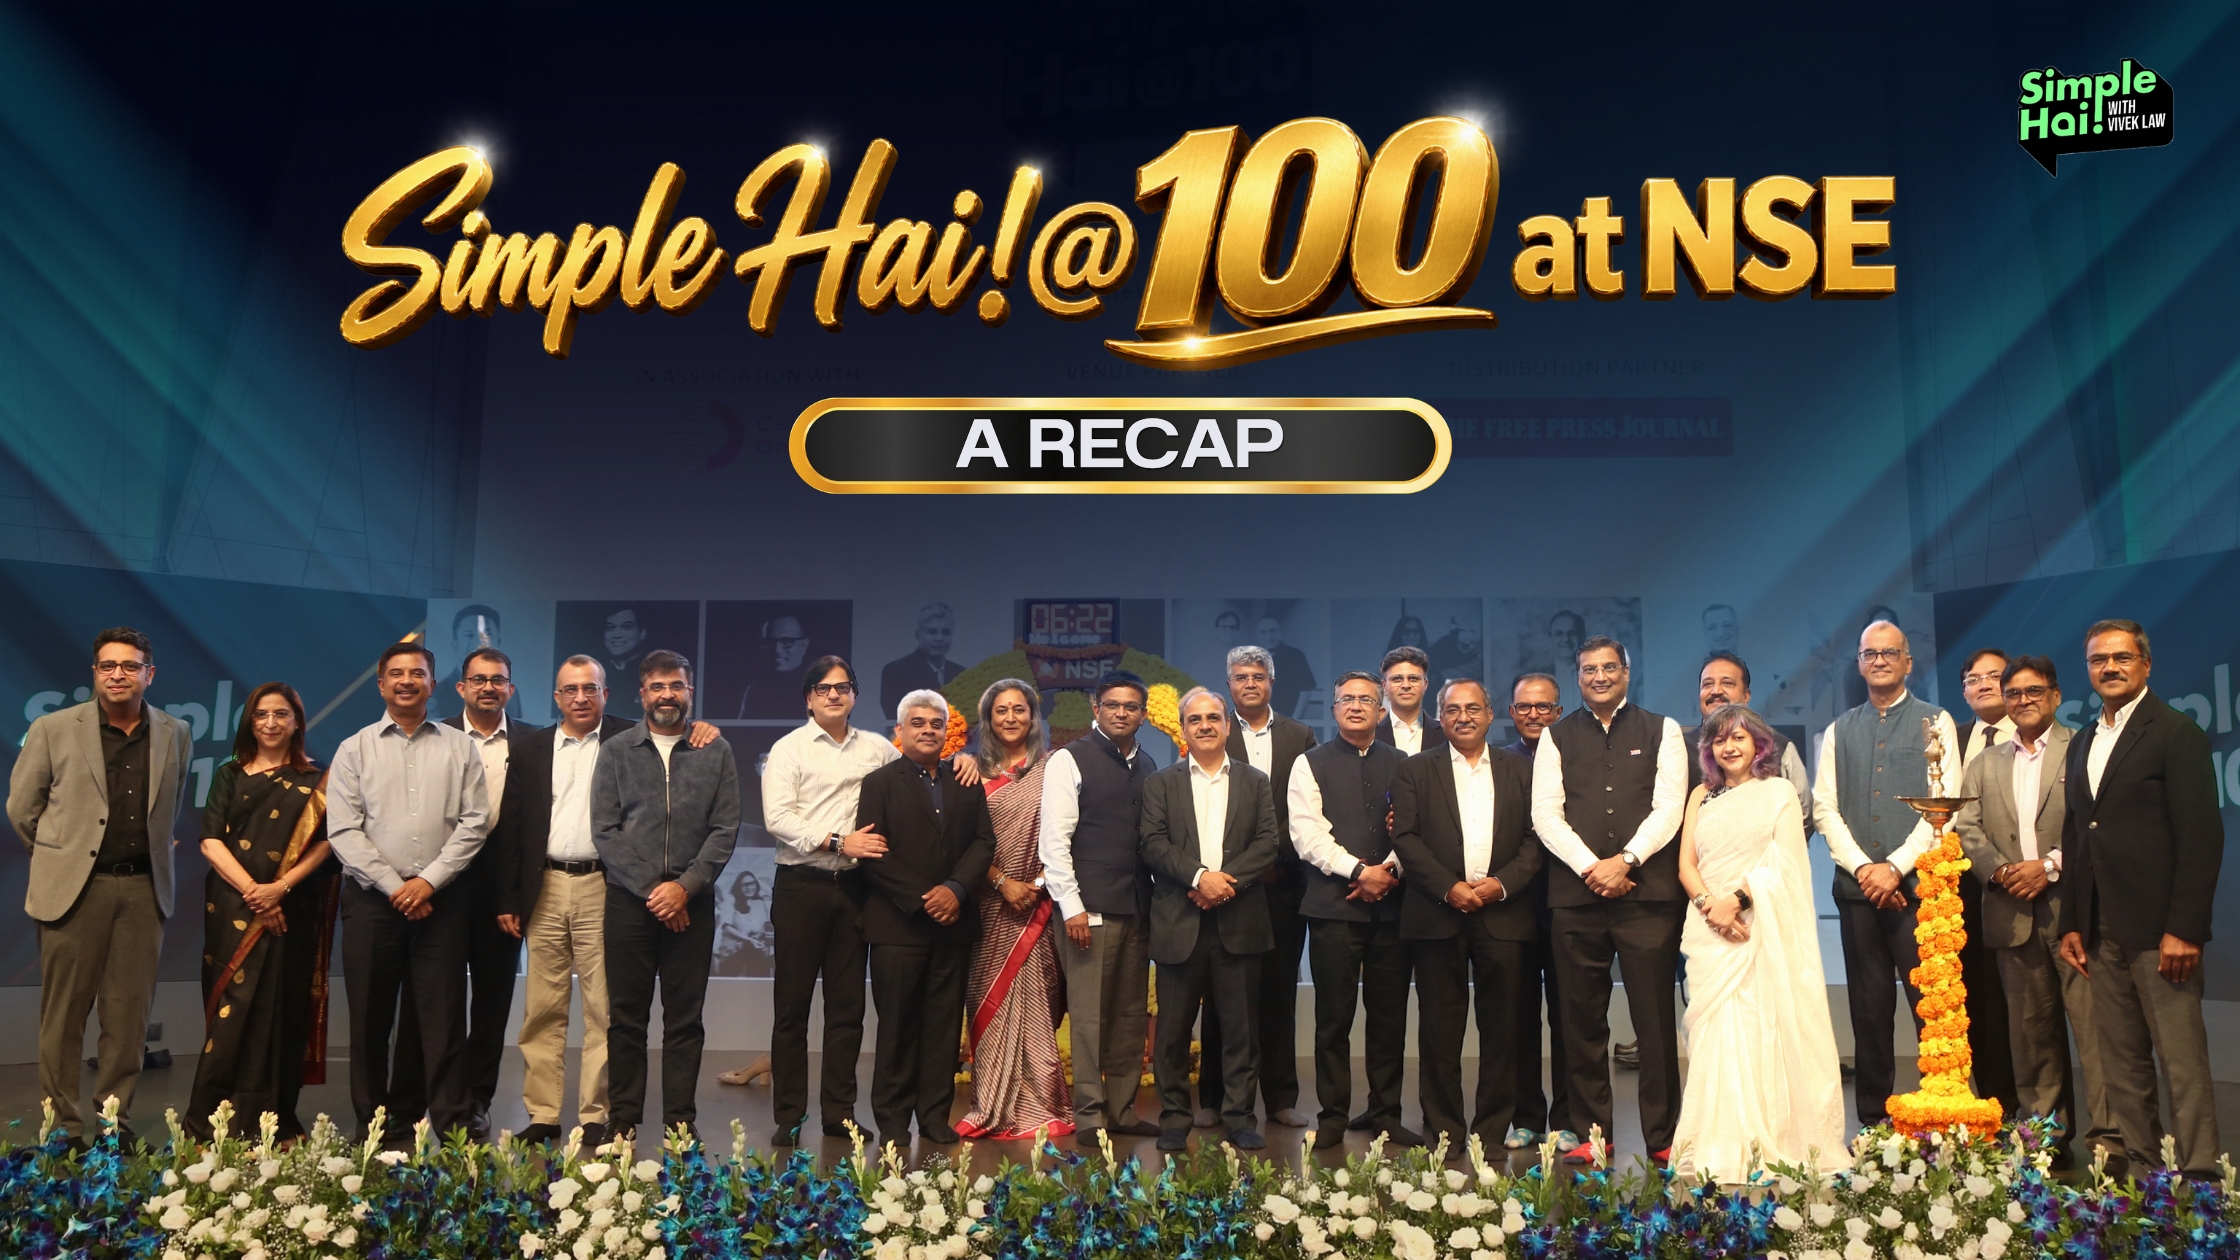
From financial awareness to financial confidence, Simple Hai! marks 100 episodes with a celebration of conversations, learning and the people behind the journey. A hundred episodes is more than a number. For Simple Hai!, it represents years of conversations aimed at making money easier to understand. The milestone was celebrated with the Simple Hai! @ 100 event, bringing together the people who have shaped, supported and powered the show. The celebration reflected on the journey of building a financial education platform around one simple idea: finance does not have to feel complicated.
From Awareness To Confidence
Over its journey, Simple Hai! has explored subjects ranging from investing and wealth creation to retirement planning and everyday money decisions.
The show’s conversations have also reflected how India’s financial landscape has changed.
Mutual funds, investing and personal finance have become more accessible to younger audiences. Digital platforms have further changed how people learn about money.
The show has reached audiences beyond India’s major metros, with viewers across more than 15 countries.
It has also crossed 38 million impressions and nearly 5 million views, reflecting the growing demand for accessible financial education.
The People Behind Simple Hai!
The celebration also recognised the team working behind the camera.
Co-founders Aparna Joshi, Harish Patil and Deepak Karna joined Law during the event, highlighting the collaborative effort behind the platform.
The wider OneNative Studio team was also brought on stage as part of the celebration.
That moment reinforced an important part of the show’s journey.
A finance platform may have a host at the centre, but building 100 episodes requires researchers, producers, editors, designers and everyone working behind the scenes.
A Conversation With Ashishkumar Chauhan
Ashishkumar Chauhan, MD and CEO of the National Stock Exchange, also joined the celebrations through a conversation and message recognising the milestone.
He highlighted the role of financial media in making investment conversations more accessible.
The discussion also looked at how Indian investors have changed over the years.
Law recalled a time when mutual funds were far less familiar to ordinary investors. Today, financial products and investment information are significantly more accessible.
The challenge has consequently shifted from access to understanding.
The Philosophy Behind The Show
One recurring idea from the celebration was the importance of knowledge.
A story from India’s financial markets captured that philosophy particularly well.
Veteran brokers once suggested that while people may worship Lakshmi, the goddess of wealth, they should remember Saraswati, the goddess of knowledge, every day.
For Simple Hai!, that idea fits the journey.
Financial confidence cannot come only from having access to products. It also requires knowledge, discipline and the confidence to ask questions.
What’s Next For Simple Hai!?
Reaching 100 episodes is being treated as a milestone rather than a finish line.
The platform plans to explore artificial intelligence and other technologies to make financial education more accessible.
The newly launched Simple Hai! website will also bring together its podcasts and financial education content.
As the show enters its next phase, its central promise remains unchanged.
Make finance simpler. Make financial conversations more accessible. And help more Indians become confident with their money.
For Simple Hai!, 100 episodes are therefore less about looking back and more about asking what comes next.
Gold has long been India’s preferred store of wealth. It is bought during festivals, gifted at weddings and passed down through generations. But while Indian households continue to accumulate the precious metal, much of it remains locked away in lockers, generating little economic value.
According to Mahendra Luniya, Founder Chairman, Vighnaharta Gold Ltd., this vast stockpile of household gold represents one of India’s biggest untapped economic opportunities. Speaking on the Simple Hai! podcast hosted by veteran business journalist Vivek Law, Luniya argued that digitising gold ownership and bringing idle gold into the formal financial system could unlock liquidity, reduce import dependence and reshape how Indians invest in the precious metal.
Gold Goes Digital
Luniya compared the evolution of gold ownership to the transformation witnessed in equity markets and payments over the last two decades.
“Shares moved from paper certificates to demat accounts. Cash moved from wallets to UPI. Gold is now following the same path,” he said.
With prices touching around ₹1.5 lakh per 10 grams, purchasing physical gold has become increasingly expensive for many households. Digital platforms, however, allow investors to start with significantly smaller amounts.
“You can now buy gold for as little as ₹150,” Luniya said, adding that digital ownership makes regular investing possible, much like a systematic investment plan (SIP). Instead of waiting to accumulate enough money to buy jewellery or coins, investors can gradually build their gold holdings over time.
From Investment to Jewellery
While digital gold is often viewed as a substitute for physical ownership, Luniya believes it actually complements traditional buying habits.
He explained that investors can accumulate gold digitally over several years and eventually convert those holdings into jewellery whenever required, particularly for weddings or family occasions.
A key innovation enabling this transition is the Electronic Gold Receipt (EGR), an exchange-traded instrument backed by physical gold stored in regulated vaults. According to Luniya, EGRs could eventually allow investors to transfer gold directly from their demat account to a jeweller, paying only the making charges or any additional quantity required.
“This makes gold accumulation far more efficient while still allowing families to eventually own physical jewellery,” he said.
Trust Through Standardisation
Luniya also highlighted the impact of mandatory hallmarking in improving consumer confidence.
Earlier, buyers often had little certainty about the purity of jewellery, with many discovering years later that ornaments sold as 22-carat gold were of lower quality. Today, BIS hallmarking and digital verification have standardised quality, making transactions significantly more transparent.
He believes this increased trust provides the foundation for wider adoption of digital gold ownership.
Unlocking a Sleeping Asset
According to Luniya, India’s privately held gold is effectively a “sleeping asset.”
While households continue buying gold every year, the country also imports hundreds of tonnes annually, placing pressure on foreign exchange reserves.
“If even a small portion of the gold already lying in Indian homes becomes financially productive, it can release enormous liquidity into the economy,” he said.
That liquidity, he argued, could support businesses, improve access to credit and reduce dependence on fresh imports.
Rather than encouraging people to stop buying gold, Luniya advocates changing how it is accumulated and utilised.
Lessons From History
During the discussion, Luniya referred to historical examples to underline gold’s strategic importance.
He cited the United States’ gold policies during the Great Depression and India’s decision to pledge gold reserves during the 1991 balance-of-payments crisis as examples of how gold has served as a critical financial asset during periods of economic stress.
His broader point was that gold should not merely remain locked away but should be capable of supporting economic activity whenever required.
Why Gold Remains Relevant
The conversation also touched upon the resurgence of gold globally.
Luniya noted that central banks across the world have increased their gold purchases amid geopolitical tensions, rising sovereign debt and efforts to diversify reserves beyond the US dollar.
Against this backdrop, he believes India’s own household gold reserves can play a far greater role in strengthening the country’s financial resilience.
Among the various investment avenues available today—including Gold ETFs, digital gold and other market-linked products—he identified Electronic Gold Receipts as one of the most promising developments because they combine the security of physical gold with the convenience of electronic ownership.
The Road Ahead
Luniya believes younger investors are already leading the shift towards digital assets.
Unlike previous generations, who primarily associated gold with jewellery, today’s investors are increasingly comfortable owning financial assets electronically while retaining the flexibility to convert them into physical form whenever required.
For him, the future of gold lies not in replacing tradition but in modernising it.
Families will continue buying jewellery for emotional and cultural reasons, but the process of saving and investing in gold is likely to become increasingly digital. If that transition gathers pace, Luniya believes India’s vast household gold reserves could evolve from being a passive store of wealth into a productive financial asset—one that benefits not only individual investors but the broader economy as well.
-
 News4 weeks ago
SC Says No Stay On New UPI Charges Above ₹2,000
-
 Podcast1 year ago
Nitin Jain: From IIT to Investment Titan, Managing ₹60,000 Crore AUM
-
 News1 month ago
NSE Makes Long-Awaited Market Debut After ₹22,562-Crore IPO
-
 Explainer5 months ago
How Much SIP Do You Need to Build ₹1 Crore? The Power of Time and Compounding
-
 Podcast2 years ago
From ₹1 Lakh Lost to Managing ₹650 Crore: How Divam Sharma of Green Portfolio Built a Fundamental Investing Approach
-
 Podcast4 months ago
Can ₹200 SIPs Create India’s Next Investing Revolution? Ravi Kumar Jha’s Big Bet On Financial Inclusion
-
 Podcast1 year ago
From ₹1 Lakh Lost to Managing ₹650 Crore: How Divam Sharma of Green Portfolio Built a Fundamental Investing Approach
-
 News2 weeks ago
UPI Charges on Payments Above ₹2,000 Delayed Until After Diwali