Explainer
From Cash To QR Codes: How India Is Changing The Way It Spends
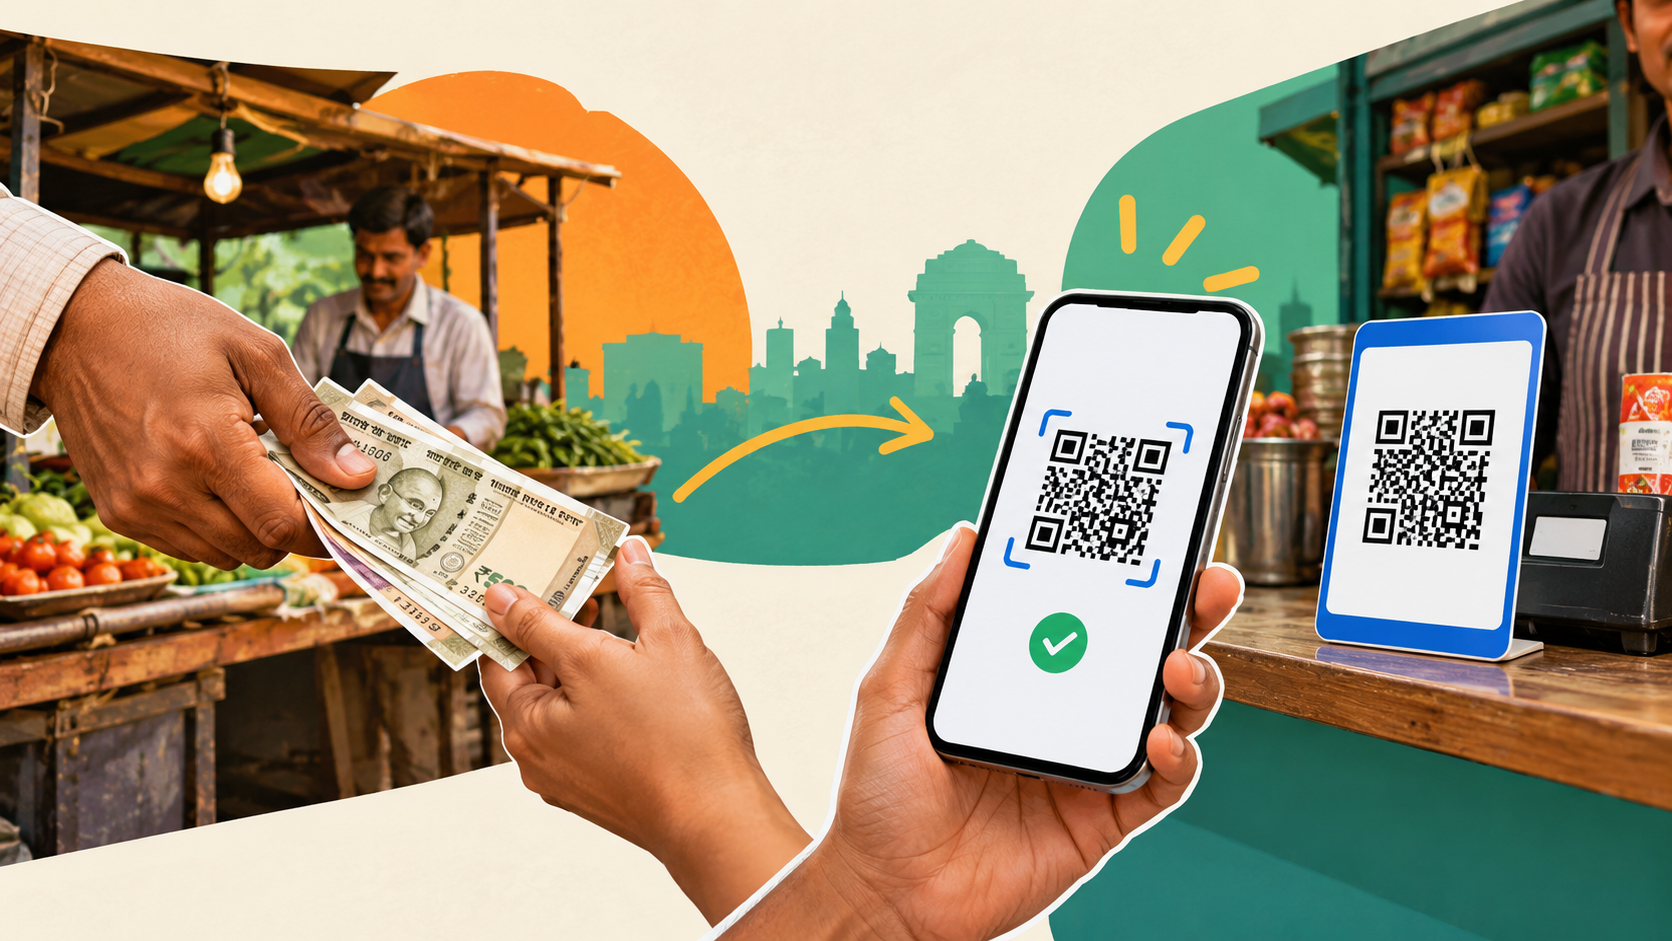
Think about the last time you actually carried cash. Maybe you had a few notes in your wallet for emergencies. But for your morning coffee, cab ride, grocery run, dinner or even splitting a ₹300 bill with a friend, you probably reached for your phone instead.
That small change in everyday behaviour is part of a much bigger shift happening across India. The country is increasingly scanning QR codes and withdrawing less cash. And while India is not completely cashless, the way people pay, spend and manage their money is clearly changing.
India is scanning more and withdrawing less
The numbers show just how quickly payment habits are changing. According to data reported by The Economic Times, the number of UPI QR codes in India rose 16.9% year-on-year to 792.6 million by June 2026. At the same time, ATM withdrawals fell 11% in volume terms, while debit-card ATM withdrawals declined 8.6%.
The same data also shows that online shopping is becoming a bigger part of card spending. Online purchases accounted for around 63% of total credit-card spending, while debit-card transactions at physical point-of-sale terminals fell 12.3%.
In simple terms, more of our money is moving through screens instead of wallets.
And Mumbai is right in the middle of it
This shift is particularly visible in India’s big cities. According to certain media reports, Mumbai Suburban accounted for around 2.49% of all UPI transactions in the country, second only to Bengaluru Urban at 2.86%. Pune followed at 1.86%. The data also shows that urban areas contribute more than half of UPI transactions, highlighting how deeply digital payments have become part of everyday city life.
For someone living in Mumbai, paying digitally can feel almost routine. Your local grocery store has a QR code, the chai shop has one, the auto driver has one, and your flatmate can send you a UPI request for the electricity bill. You don’t necessarily need to plan ahead and withdraw ₹2,000 from an ATM anymore. Your phone has effectively become your wallet.
But UPI isn’t just replacing big cash payments
One of the more interesting changes is happening with small everyday purchases. Data analysed by Mint shows that retail payments now make up 64% of UPI transactions, up from 37% in mid-2021. At the same time, the average retail UPI transaction has fallen from ₹648 to ₹425.
That tells us something important. UPI isn’t only being used for paying rent, transferring money or making large purchases. It is increasingly being used for the ₹50 coffee, ₹120 lunch, ₹200 auto ride and ₹400 grocery bill. Basically, the smaller the payment, the easier it has become to not think twice about how you’re paying for it.
And that brings us to the personal-finance question: does spending digitally make spending easier?
Does spending digitally make spending easier?
Cash has a physical limit. If you have ₹1,000 in your wallet and spend ₹700, you can actually see that you have ₹300 left. Digital money doesn’t give you that same physical reminder.
You can make five ₹200 payments throughout the day without ever seeing your wallet get thinner. That’s convenient, but it can also make small expenses easier to overlook. ₹100 for coffee, ₹180 for a cab, ₹250 for lunch and ₹120 for a quick online order may not feel like particularly large purchases on their own. But several small digital payments can quietly add up over a week or a month.
This doesn’t mean UPI is making people financially irresponsible. It simply means that when spending becomes frictionless, tracking it becomes more important.
The good part: your money leaves a digital trail
There is also a major personal-finance advantage to digital payments. Unlike cash, digital transactions are automatically recorded. Your bank statement or UPI app can show where your money went, making it easier to look back at your spending.
That can help you understand how much you are actually spending on food, cabs, online shopping or subscriptions. You can also look back at those small ₹100–₹500 payments that seemed insignificant when you made them but may add up to a sizable amount by the end of the month.
The data is already there. The trick is actually looking at it.
But cash isn’t disappearing completely
Calling India a completely cashless country would be an overstatement. Mint reports that a 2025 RBI study found greater UPI adoption was associated with lower demand for cash, while ATM cash withdrawals as a share of GDP have also fallen over time.
At the same time, UPI adoption is spreading beyond India’s biggest cities. The combined share of India’s top 10 districts in overall UPI transaction volume fell from 25.2% in 2019 to 17.4% in April-June 2026, suggesting that digital payments are becoming more widespread geographically.
So the story isn’t really that cash is dead. It’s that cash is no longer the only convenient way to pay.
What does this mean for your personal finances?
The shift to digital payments doesn’t require you to change how you pay. But it may require you to change how you track what you pay.
If you rarely carry cash anymore, try giving your digital spending the same attention you once gave your wallet. Check your UPI and bank transactions regularly, set a monthly limit for discretionary spending and keep an eye on recurring small expenses.
Most importantly, don’t let the convenience of a QR code make every purchase feel too small to matter. Because whether the money leaves your wallet or your bank account, it is still your money.
India may be scanning more and withdrawing less. But your spending still needs a plan.
Sources: Mint, MoneyControl and The Economic Times
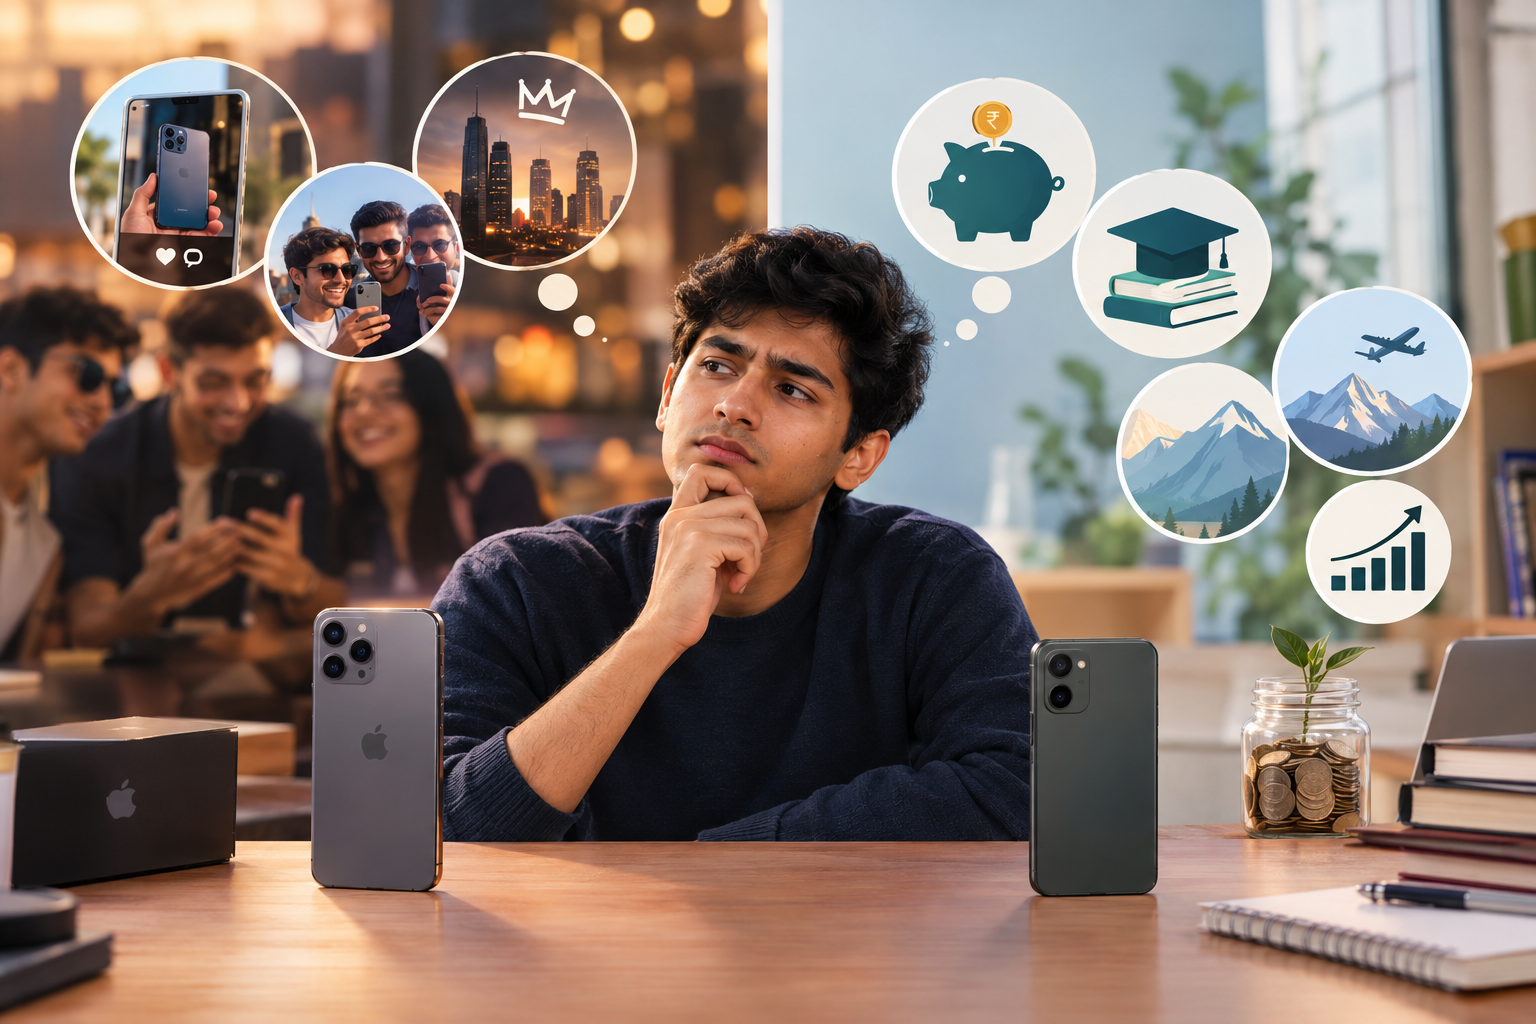
For young earners, buying an expensive smartphone can feel like a reward for hard work. But when does the desire to look successful start getting in the way of building wealth?
The first salary brings a new kind of freedom. A young professional can finally buy things without asking for money. And often, the first big purchase is a smartphone.
Friends are flaunting their latest devices, Instagram is flooded with unboxing videos and a perfectly functional phone suddenly feels outdated. An ₹80,000 smartphone starts looking less like an expense and more like a reward for all the hard work.
But there is a difference between buying something because it adds value and buying it because it makes life look better to others.
India’s premium smartphone obsession
India’s smartphone market is moving towards premium devices. According to Counterpoint Research, smartphones priced above ₹30,000 accounted for 22% of smartphone shipments in India in 2025, their highest ever share.
A July 2026 Counterpoint Research survey also found that 46% of prospective smartphone buyers in India were willing to stretch their budgets to purchase their preferred phone despite price increases. Among consumers aged 25 to 30, the figure was 52%.
These numbers do not mean everyone buys expensive phones for status. Better cameras, performance and software support can justify the premium. However, they highlight how willing consumers can be to spend beyond their original budgets for a device they desire.
For young professionals still building their savings, this creates a dilemma: should the money go towards a premium phone or towards financial security?
What does an ₹80,000 phone actually cost?
Consider someone earning ₹40,000 a month and choosing between a ₹15,000 smartphone and an ₹80,000 device.
The premium phone costs twice their monthly salary before deductions. The budget alternative costs less than half of one month’s salary.
The difference is ₹65,000. That money could help build an emergency fund, pay for professional training or contribute towards future investments.
Of course, a premium phone may offer better features and a longer useful life. The point is not that expensive phones are always a bad purchase. It is whether the additional benefits justify the additional cost.
The EMI trap
Monthly instalments can make an expensive purchase feel manageable. Instead of thinking about ₹80,000, buyers focus on a smaller monthly payment.
But an affordable EMI does not automatically make a purchase financially sensible.
If repayments leave little money for savings, rent or other priorities, the phone may be stretching the budget more than it appears. Interest and fees can also increase the total cost.
The real cost of keeping up
The phone that attracts compliments today may become ordinary tomorrow. A newer model arrives, attention shifts and the excitement fades. The money spent, however, does not return.
For someone whose main motivation is social recognition, this creates an uncomfortable trade off. The owner bears the full cost while the approval may last only a short time.
Choosing a budget phone and keeping the ₹65,000 difference could create room for savings, experiences or investments. For illustration, ₹65,000 invested at an assumed annual return of 10% could grow to approximately ₹1.05 lakh over five years, before taxes and charges. Actual returns are not guaranteed.
So, should young earners buy budget phones?
Not necessarily. A premium phone can be worth the money when its features genuinely matter and the purchase fits comfortably within the buyer’s finances.
But before upgrading, it helps to ask: is the phone being purchased for its usefulness or because everyone else seems to have one?
Affordable smartphones have expanded the choices available to consumers. For everyday needs such as messaging, digital payments, browsing and streaming, a budget device may be sufficient.
A smartphone can signal purchasing power, but it cannot tell anyone how financially secure its owner really is.
The real flex is not owning the most expensive phone. It is being able to afford the things that matter without sacrificing the financial freedom that makes them possible.
There was a time when buying a designer bag was fairly straightforward: you liked it, you could afford it, and you bought it.
Now, things are a little different.
People are booking appointments, joining waitlists and hunting down specific colours, materials and limited-edition pieces. There are collectors with entire rooms dedicated to their handbags. And increasingly, buyers aren’t looking at these bags only as fashion purchases; they are looking at what the bag could be worth years down the line.
That got me thinking: when did a handbag start looking like an investment?
The Numbers Are Making The Case
According to the Knight Frank Luxury Investment Index, handbags were the best-performing luxury collectible category in 2024, gaining 2.8%.
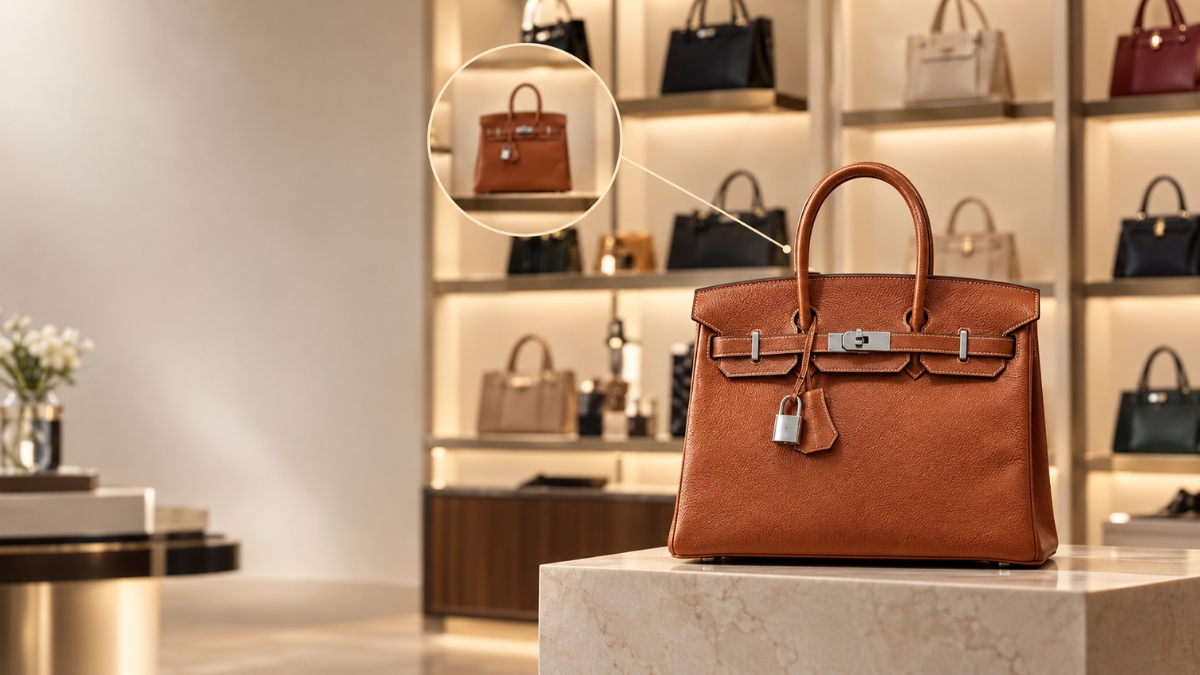
Economic Times also highlighted how certain luxury handbags can sell for significantly more in the resale market than their original retail price. One example cited was an Hermès Birkin 25, which retailed at around ₹10.2 lakh but was selling for roughly ₹18 lakh in the resale market.
That’s a pretty interesting premium for something that is technically still a handbag.
Forbes has been making a similar argument for years. Its research has looked at designer handbags particularly sought-after Hermès pieces as an alternative investment, comparing their appreciation with traditional luxury assets such as art.
Of course, that doesn’t mean your wardrobe is suddenly a stock portfolio. But it does show that something interesting is happening in the luxury market.
Scarcity Is Doing A Lot Of The work
The most valuable handbags aren’t necessarily the most expensive ones. They’re often the ones people can’t easily get.
Limited production, discontinued designs, rare colours and materials, celebrity associations and strong brand demand can all contribute to resale value.
And that explains the waitlists.
The scarcity itself becomes part of the product. If everyone could walk into a store tomorrow and buy the same bag, some of that exclusivity and potentially some of its resale appeal would disappear.
It’s the same basic idea we see with many collectibles: when supply is limited and demand stays strong, people are willing to pay more.
This Is Also Creating A New Kind Of Collector
There are serious collectors building entire portfolios of handbags. Some buy specific models because they believe they will hold their value. Others look for pieces that are rare or difficult to find.
And yes, there are people whose collections are large enough to require dedicated storage.
At that point, we’re moving beyond fashion. We’re talking about an asset that someone is deliberately acquiring, preserving and potentially reselling.
And Then There’s The Collateral Angle
Here’s where things get even more interesting.
In some markets, specialist lenders allow owners to borrow against valuable luxury handbags, using them as collateral. In simple terms, the bag is valued and the owner can potentially access a loan against that value.
But this is where one should draw the line between “valuable asset” and “investment.”
Not every designer bag will qualify. And not every bag will be appreciated. Brand, model, condition, authenticity, rarity and resale demand can all influence its value.
So, are designer bags actually investments?
Sometimes. But not every expensive handbag is an investment. A stock can generate dividends. A bond can generate interest. A property can generate rent. A handbag doesn’t do any of that.
Its investment potential comes from what someone else may be willing to pay for it later. And that makes the market much more dependent on trends, scarcity and consumer demand.
So yes, a ten lakh handbag could potentially become more valuable over time.
But that doesn’t mean spending ten lakh on a handbag is automatically a smart financial decision. The smarter way to look at it may be this: a designer bag can be a luxury purchase that happens to have investment potential, not an investment that happens to be a bag.
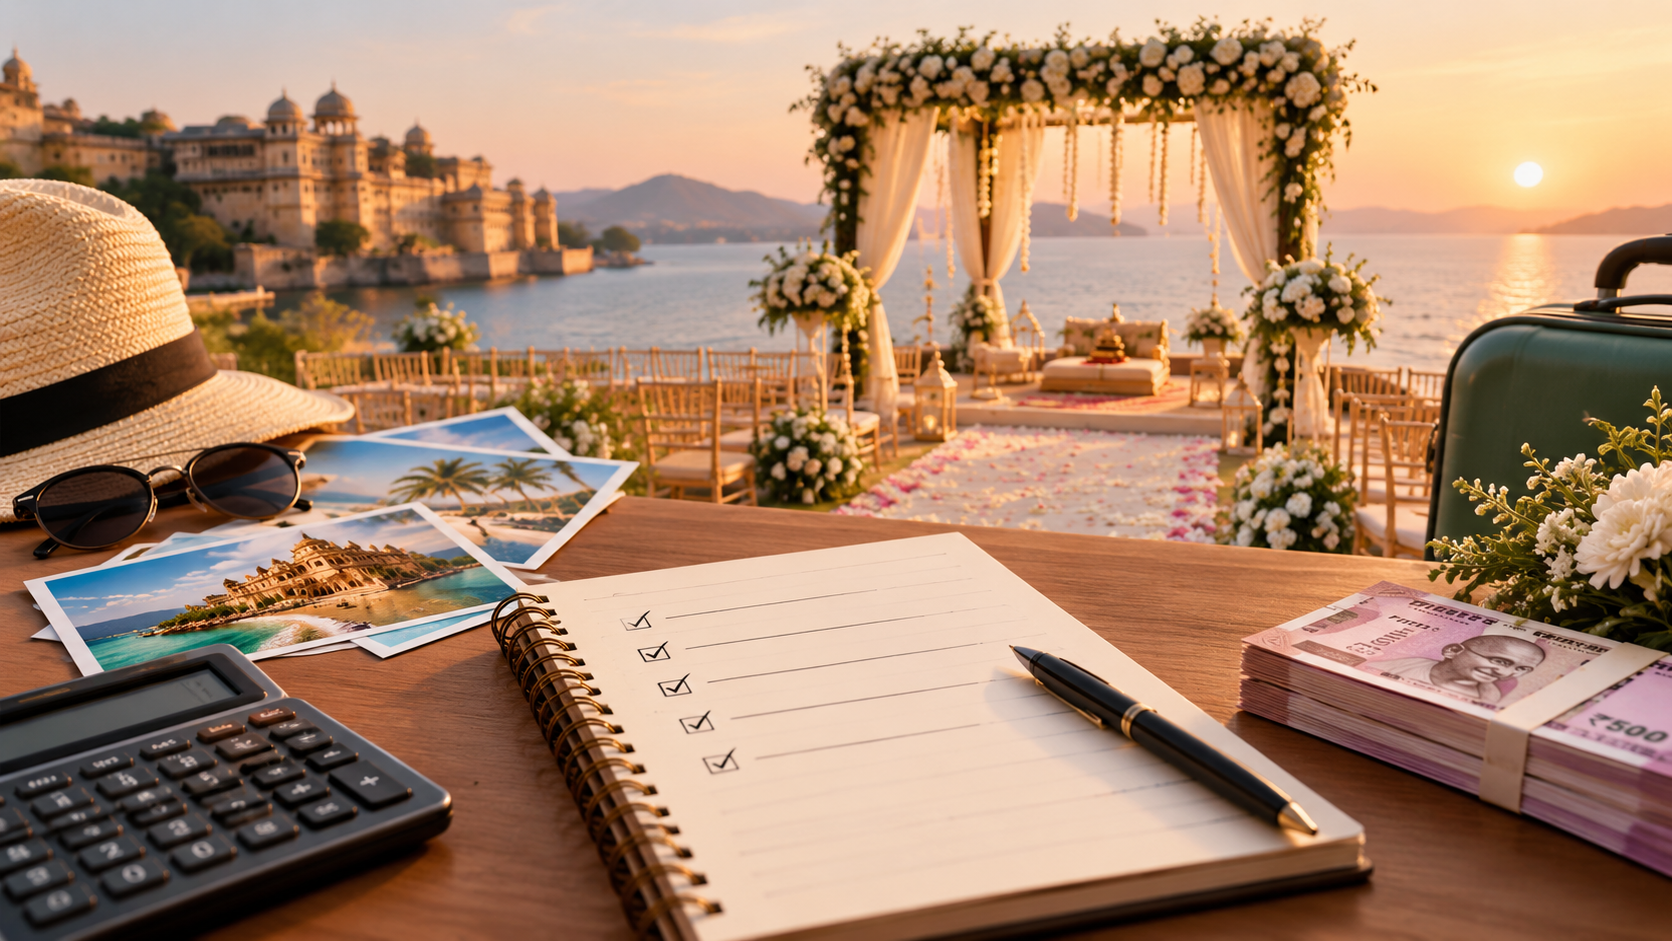
Destination weddings are having a big moment. But before you book that beach resort or palace, there’s one thing worth checking first: Can your budget actually handle it? A 2026 report estimates the average destination wedding in India at around ₹58 lakh, with destination weddings expected to make up an even larger share of Indian weddings in the coming years. And that ₹58 lakh isn’t just a venue bill.
Your Guest List Is Your First Expense
Every additional guest can mean another room, meal, transfer, activity and possibly a flight.
So before deciding on the destination, decide how many people you’re actually willing to spend on.
A smaller guest list could leave you with more room in the budget for the things you genuinely care about without pushing your total spending higher.
The Destination Changes The Math
Goa, Udaipur, Jaipur or a luxury resort in the hills may look very different on Instagram and on the final bill.
You need to factor in:
- Venue and accommodation
- Food and beverages
- Guest travel
- Local transportation
- Décor and entertainment
- Photography and makeup
- Vendor travel and accommodation
And during the peak wedding season, higher demand can also mean higher prices.
If your dates are flexible, comparing peak-season and off-season prices could help bring the cost down.
Don’t Budget Only For The Wedding Day
A destination wedding often means paying for multiple days.
That means your budget needs to account for hotel nights, meals, transfers and all the little expenses that tend to appear once the wedding planning begins.
One useful approach is to create an all-in budget before paying any advance.
Not: Venue = ₹30 lakh
But: Wedding = venue + stay + travel + food + vendors + décor + contingency.
And Please Keep A Buffer
Wedding expenses have a habit of growing. An extra room here. A last-minute vendor there. Additional décor. A delayed flight.
Keep a separate contingency amount instead of putting every available rupee into the wedding. And if you’re considering wedding insurance, check exactly what the policy covers, its exclusions and claim limits before buying it.
The Money Checklist
Before booking that dream destination, ask:
- What’s our maximum budget?
- How many guests are we actually paying for?
- What’s the total travel and accommodation cost?
- Can changing the date reduce the cost?
- Have we included a contingency fund?
- Are we borrowing more than we’re comfortable repaying?
Because a beautiful wedding shouldn’t come with a financial hangover.
The goal isn’t to spend the most. It’s to celebrate without spending the next few years recovering from it.
Sources: Economic Times and 2026 wedding-industry estimates.
Disclaimer: Costs are indicative and may vary depending on the destination, guest count, wedding date and venue.
-
 Podcast1 year ago
Nitin Jain: From IIT to Investment Titan, Managing ₹60,000 Crore AUM
-
 News3 weeks ago
SC Says No Stay On New UPI Charges Above ₹2,000
-
 News4 weeks ago
NSE Makes Long-Awaited Market Debut After ₹22,562-Crore IPO
-
 Explainer5 months ago
How Much SIP Do You Need to Build ₹1 Crore? The Power of Time and Compounding
-
 Podcast2 years ago
From ₹1 Lakh Lost to Managing ₹650 Crore: How Divam Sharma of Green Portfolio Built a Fundamental Investing Approach
-
 Podcast4 months ago
Can ₹200 SIPs Create India’s Next Investing Revolution? Ravi Kumar Jha’s Big Bet On Financial Inclusion
-
 Podcast1 year ago
From ₹1 Lakh Lost to Managing ₹650 Crore: How Divam Sharma of Green Portfolio Built a Fundamental Investing Approach
-
 Podcast2 months ago
Simple Hai! @ 100: Celebrating a Milestone in Making Finance Simple