Explainer
Festive Shopping: 5 Things to Check Before Making an Online Payment
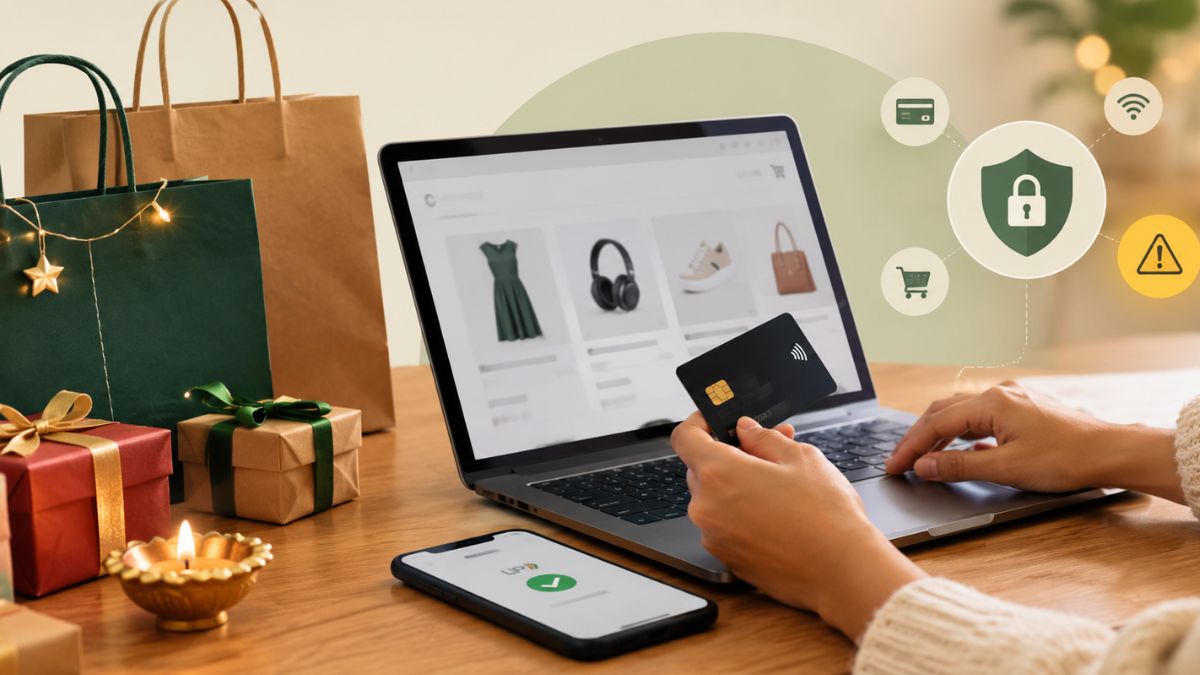
Festive sales are the perfect time to shop for clothes, electronics, gifts and everything else on your wishlist. With attractive discounts, cashback offers and limited-period deals, it is easy to get carried away while shopping.
But not every offer is as good as it looks.
In the rush to grab a bargain, shoppers may overlook fake websites, unreliable sellers and suspicious payment links. One wrong click or careless transaction could turn a good deal into a financial loss.
Whether you are paying through UPI, a debit card or a credit card, a few simple precautions can help keep your money safe.
Here are five things to keep in mind before completing an online purchase.
1. Check if the Shopping Website Is Genuine
Before entering your payment details, make sure you are shopping on the official website or app.
Fraudsters often create fake websites that look almost identical to popular shopping platforms. Sometimes, the only difference is a small spelling mistake or an unusual website address.
Instead of clicking on random links received through messages, emails or social media, visit the official website directly or use the brand’s verified app.
Also, remember that the padlock symbol or ‘HTTPS’ in a website address does not automatically mean the website is genuine. It only indicates that the connection is encrypted.
2. Verify the Seller Before Placing an Order
A product being sold at an unusually low price can be tempting, especially during festive sales. However, it is important to check who you are buying it from.
Before placing an order, look at customer reviews, seller ratings, return policies and refund conditions. Check whether the seller has proper contact details and customer support.
Be careful if someone asks you to make a payment outside the shopping platform, transfer money directly to a personal bank account or complete the purchase through a messaging app.
Such requests can be warning signs of fraud. If something goes wrong, getting your money back may become much more difficult.
3. Double-Check Payment Details Before Approving
Even when you use a familiar payment method, always verify the transaction before confirming it.
For UPI payments, check the recipient’s name and the amount displayed on your screen. Remember, you do not need to enter your UPI PIN to receive money.
If you are paying through a debit or credit card, verify the transaction amount before entering your OTP or approving the payment. Avoid saving your card details on unfamiliar websites.
Some payment security features also help reduce risks. For example, card tokenisation replaces actual card details with a digital token, helping protect sensitive information during transactions.
However, technology alone cannot prevent every fraud. Checking the payment details yourself is still important.
4. Don’t Fall for Deals That Look Too Good to Be True
Flash sales, countdown timers and massive discounts often create a sense of urgency. They make shoppers feel that they need to buy something immediately before the offer disappears.
While many festive offers are genuine, scammers also use these tactics to trick people into clicking suspicious links or sharing financial information.
Before making a purchase, compare prices across trusted shopping platforms. Check whether the offer is mentioned on the brand’s official website or app.
Also, look at the final bill. Delivery fees, taxes and additional charges can sometimes make a seemingly attractive deal much more expensive.
Be particularly cautious of offers asking you to pay money upfront to receive cashback, claim a reward or win a prize.
5. Never Share Your OTP, UPI PIN or Banking Password
Your OTP, UPI PIN and banking passwords are private. Never share them with anyone, even if the person claims to be calling from your bank, a payment company or a shopping platform.
Fraudsters may pretend that a payment has failed, a refund is pending or your account needs verification. They may then ask you to share an OTP or approve a payment request.
Instead of responding to such calls or messages, contact your bank or the shopping platform through its official customer support channels.
If you receive an OTP or payment approval request for a transaction you did not initiate, do not approve it.
What Should You Do If You Suspect Online Payment Fraud?
Being careful before making a payment is important, but keeping track of your transactions afterwards matters too.
Check your bank statements and payment notifications regularly, especially during festive sales when you may be making several purchases.
If you notice an unauthorised transaction, contact your bank immediately and request that the affected card or payment facility be blocked, if required.
You can also report suspected cyber financial fraud through India’s National Cyber Crime Helpline at 1930 or the official website cybercrime.gov.in.
A Good Deal Shouldn’t Come at the Cost of Your Money
Festive shopping should be about enjoying the season, not worrying about losing money to online scams.
A little caution before clicking on a link, choosing a seller or approving a payment can make a big difference.
So, before you hit that ‘Buy Now’ button, take a moment to check. Because saving money on a purchase only matters when your money is safe in the first place.
Source: MoneyControl
Having health insurance does not always mean you will pay nothing during a medical emergency. From room rent limits to consumables, here’s why out-of-pocket expenses can add up and what you can do about them.
Buying health insurance is an important step towards protecting your finances. But when a hospital bill arrives, many policyholders discover that their insurance does not cover every expense.
The difference between what your insurer pays and what you actually owe can become a significant financial burden, especially during an already stressful medical emergency.
This is where understanding your policy becomes important. The right add-ons can help reduce these gaps, but buying every available feature may not always be necessary.
Why does your health insurance fall short?
Even when a treatment is covered, certain policy conditions can leave you paying part of the bill yourself. Here are some common reasons.
1. Room rent limits
Some health insurance policies place a limit on how much you can spend on a hospital room. If you choose a room that costs more than your policy allows, you may have to pay the difference. Depending on the policy’s terms, other linked hospital expenses may also be affected.
Checking room rent limits before choosing a policy can help you avoid unexpected costs.
2. Restoration benefits
A restoration benefit replenishes your sum insured after it has been used, subject to the policy’s conditions. While this can be useful if you need further treatment or make multiple claims, it is important to understand when the benefit becomes available and how it can be used.
A policy with a restoration benefit is not automatically the best choice for everyone. Its usefulness depends on your coverage needs and the terms attached to it.
3. Consumables not covered by your policy
Hospital bills can include items such as gloves, masks, syringes and other medical supplies. These expenses, often called consumables, may not be covered under every health insurance policy.
An add-on that covers eligible consumables can reduce this gap. However, check which items are included, since the benefit may not cover every non-medical expense.
4. Inadequate employer-provided insurance
Many employees depend on the health insurance provided by their employer. While this offers a useful starting point, the coverage may not be enough for every medical situation.
There is also a potential risk if you change jobs or leave employment and lose access to the group policy. Having an individual health insurance policy alongside employer-provided coverage can offer an additional layer of protection.
Should you buy every health insurance add-on?
Not necessarily.
Add-ons can improve your coverage, but they also increase the premium you pay. Buying several features without understanding their benefits can mean spending more without getting meaningful additional protection.
For instance, someone whose policy already offers suitable room rent coverage may not need to prioritise an upgrade for that feature. On the other hand, someone concerned about frequent hospital visits may find broader coverage for eligible consumables useful.
The idea is to identify the gaps in your existing policy rather than simply choosing the plan with the longest list of benefits.
How to choose the right health insurance cover
Before buying a policy or renewing an existing one, consider these three things:
- Read the fine print: Check room rent limits, exclusions, waiting periods, co-payments and claim conditions.
- Compare add-ons carefully: Understand what each feature covers, its additional cost and whether it addresses a genuine gap in your policy.
- Review your coverage regularly: Your healthcare needs and financial responsibilities can change over time. Reassess whether your sum insured and policy benefits remain suitable.
Also, remember that a higher sum insured does not automatically eliminate every out-of-pocket expense. Coverage limits, exclusions and policy conditions continue to matter.
The bottom line
Health insurance is meant to protect your savings from large, unexpected medical expenses. But the protection it offers depends on more than just the amount of coverage you purchase.
Understanding what your policy pays for, what it excludes and where additional cover could help is just as important as comparing premiums.
Because when it comes to health insurance, the goal isn’t to buy the most features. It’s to avoid being caught off guard when you need your policy the most.
Discounts, limited-time offers and easy EMIs can make festive shopping exciting. But before you add another item to your cart, it’s worth asking one question: Do you really need it?
Festive sales are hard to miss. From clothes and electronics to home appliances and cars, brands promise attractive discounts, cashback offers and special deals during the festive season. With Diwali and other celebrations bringing a shopping mood, it is easy to feel that this is the perfect time to buy everything on your wishlist.
But there is a catch. Not every discount means you are saving money. Sometimes, the excitement of getting a good deal can make you spend on things you never planned to buy in the first place.
Why Do Festive Sales Make Us Spend More?
Retailers use a range of pricing strategies and psychological triggers to encourage shoppers to spend. Understanding them can help you make better financial decisions.
1. The pressure of a limited-time offer
“Offer ends tonight” or “Only a few pieces left” can make you feel that you need to buy something immediately. This creates a fear of missing out, pushing you to make quick decisions without comparing prices or thinking about whether you need the product.
2. The attraction of a big discount
A product marked down from ₹10,000 to ₹6,000 may look like a great deal. But the real question is whether you would have bought it at all if it had never been on sale.
A discount only saves you money when you were already planning to make that purchase and the final price is genuinely competitive.
3. The temptation of easy EMIs
Monthly instalments can make expensive purchases seem more affordable. A phone worth ₹60,000 may feel easier to buy when the payment is divided into smaller amounts.
However, multiple EMIs can quickly add up. Processing fees, interest charges and other costs may also increase the total amount you pay. A purchase that fits your monthly budget individually may become difficult to manage when combined with other expenses.
4. Cashback and rewards that encourage extra spending
Cashback, reward points and bank offers can make a purchase more attractive. But spending an additional ₹5,000 just to receive a small cashback is not necessarily a smart financial decision.
The benefit matters only if the purchase makes sense even without the offer.
Five Questions to Ask Before You Buy
Before making a festive purchase, take a moment to consider these five things.
- Would I buy this without the discount? If the answer is no, ask yourself whether the offer is creating a need that did not exist before.
- How often will I use it? A product you use every day may justify the expense more than something that stays unused after the festive season.
- Is this a genuine discount? Compare prices across retailers and check the final amount, including delivery charges, fees and other costs.
- What am I giving up to afford it? Money spent on an impulse purchase could otherwise go towards savings, an emergency fund, debt repayment or another financial goal.
- Can I afford it without borrowing? If you need an EMI, calculate the total repayment and check whether it comfortably fits your existing budget.
How to Shop Smart During Festive Sales
You do not have to avoid festive sales altogether. The goal is to make sure your spending works for you, rather than letting a sale decide how you spend.
Make a shopping list beforehand. Decide what you need and set a spending limit. This helps you separate planned purchases from things that simply look attractive in the moment.
Compare the final price, not just the discount. Check different platforms, look for additional fees and compare the current price with the product’s usual selling price.
Give yourself a 24-hour pause. For non-essential purchases, wait a day before placing the order. The urgency of a limited-time offer may feel less convincing once you have had time to think.
Use credit cards carefully. Cashback and reward points are useful only when you understand the terms and can manage your repayments. Avoid carrying expensive credit-card debt just to enjoy a festive offer.
Protect your savings first. Set aside money for essentials, upcoming bills and financial goals before deciding how much you can spend on festive shopping.
A Discount Is Not Always a Saving
Festive shopping can be a good opportunity to buy things you genuinely need at a lower price. But the amount displayed on a discount tag does not tell the whole story.
If you spend ₹5,000 on something you never intended to buy, you have not saved money simply because it was originally priced at ₹7,000. You have spent ₹5,000 that could have gone towards something more useful.
The smartest festive purchase is not necessarily the one with the biggest discount. It is the one that fits your needs, your budget and your financial priorities.
This festive season, enjoy the sales, but let your budget make the final decision.
Every Diwali, many Indian families buy gold. For some, it is a small gold coin. For others, it is a new ring, a necklace or a piece of jewellery they have been planning to buy for months.
Dhanteras is considered an auspicious day to buy gold, and the tradition has been part of Indian households for generations. But with gold prices changing so much this year, one question is worth asking: Should you buy gold because it is Dhanteras, or because it makes sense for your money?
The answer depends on what you are buying, why you are buying it and how much you can comfortably spend.
Gold Prices Have Changed the Way People Shop
Gold prices have seen sharp ups and downs in 2026. After reaching record highs, prices have also fallen in recent weeks.
For buyers, this might seem like a good time to shop. But even after a price drop, gold can take a big bite out of a household’s budget.
This is also changing how people shop. Some are choosing lighter jewellery, while others are considering gold coins and bars instead.
But a lower price does not automatically mean gold is affordable for everyone. Even a small purchase can cost a significant amount.
The point is simple: just because gold prices have fallen does not mean you need to buy more.
Buying Gold and Investing in Gold Are Not the Same Thing
For many families, buying gold is part of celebrating Diwali. It could be jewellery for a wedding, a gift for a loved one or simply a way to keep a family tradition alive.
There is nothing wrong with that.
But buying jewellery and investing in gold are two different things.
When you buy jewellery, you pay for more than just the gold. The final bill also includes making charges, which cover the work that goes into creating the piece, along with applicable taxes.
And if you decide to sell the jewellery later, you may not get back the full amount you spent. Making charges, for example, may not be returned.
So, even if gold prices rise, your jewellery may not give you the same return.
If you are buying jewellery to wear, enjoy it. If you are buying gold to grow your money, compare your options first.
Should You Buy Gold Now or Wait?
This is a question many people ask before Dhanteras.
Gold prices can change for several reasons, including global events, interest rates and changes in the value of the rupee. This makes it difficult to predict whether prices will rise or fall in the coming weeks.
Trying to find the perfect time to buy can become stressful, especially if you need gold for a wedding or a family occasion.
If you already know you want to buy gold, start by deciding how much you can spend. You could also consider buying in smaller amounts over time instead of trying to predict the lowest price. This does not guarantee a better deal, but it can help you avoid depending on a single day’s price.
And if the purchase is not urgent, there is no need to rush just because Dhanteras is around the corner.
Gold Jewellery, Coins or Gold ETFs: What Should You Choose?
There is more than one way to buy gold. The right choice depends on what you want from it.
Gold jewellery: If you want something to wear or gift, jewellery makes sense. Just remember to check the making charges and the final bill.
Gold coins and bars: These let you own physical gold without paying for an elaborate jewellery design. However, there may still be additional purchase costs. You should also check how easy it will be to sell them later.
Gold ETFs: These allow you to invest in gold through the stock market without storing physical gold. You generally need a demat and trading account, and there are costs and market risks to consider.
None of these options is the best choice for everyone. If you want gold to wear, jewellery may be right for you. If you want to invest, compare the costs and risks before deciding.
And remember, gold prices can fall too. Do not put all your savings into gold or use money you may need for emergencies.
Before You Buy Gold This Dhanteras, Ask Yourself Three Questions
Before heading to the jewellery store, take a moment to ask yourself three simple questions.
1. Can I afford this without borrowing?
Decide your budget before you shop. Avoid using your emergency savings or taking on expensive debt just to follow a festive tradition.
2. Am I buying it to wear or to invest?
Both are valid reasons. Knowing why you are buying gold can help you choose the right option.
3. Have I checked the final price?
Check the gold rate, purity, making charges and applicable taxes. Ask about the jeweller’s exchange and buyback rules, too.
A few simple checks can help you avoid surprises later.
Celebrate the Festival. Keep Your Finances in Mind.
Dhanteras is a time to celebrate prosperity, and buying gold can be a meaningful part of that celebration.
But being financially secure is about more than what you bring home from a jewellery store. It is also about the savings you build, the debt you avoid and the goals you work towards.
You do not have to spend a large amount to celebrate the festival. And you do not have to buy gold just because everyone else is doing it.
This Dhanteras, buy gold if it makes sense for you. Just make sure your budget decides how much you spend, not the occasion.
-
 News1 month ago
SC Says No Stay On New UPI Charges Above ₹2,000
-
 Podcast1 year ago
Nitin Jain: From IIT to Investment Titan, Managing ₹60,000 Crore AUM
-
 News1 month ago
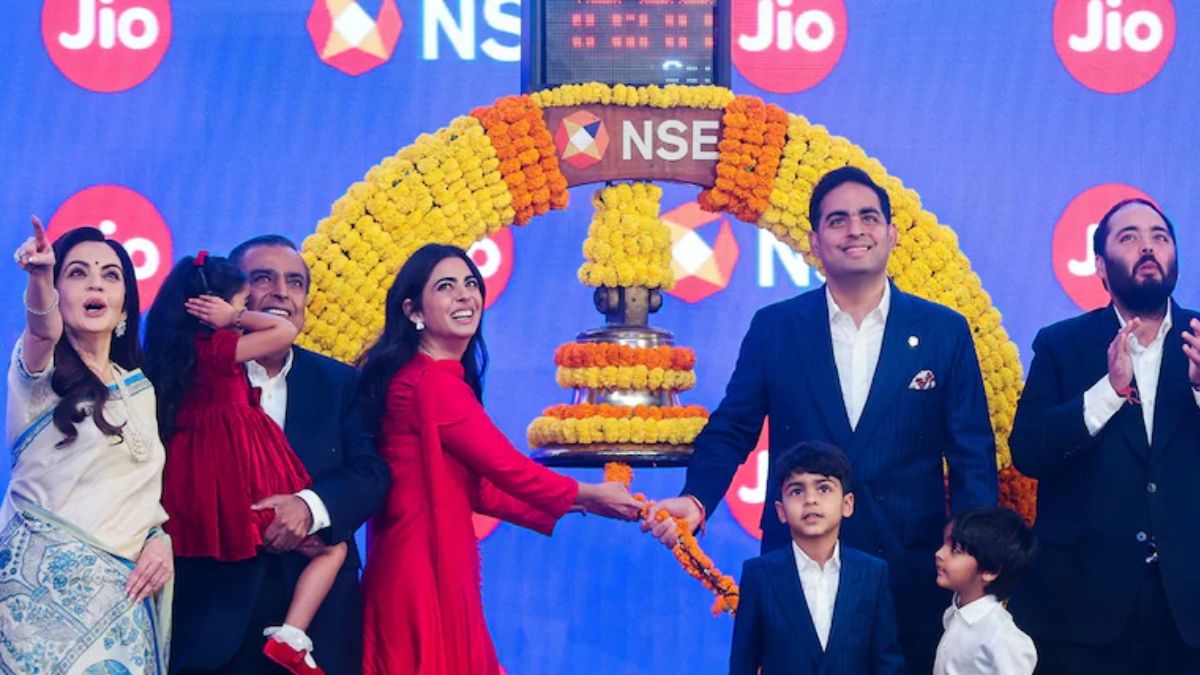
NSE Makes Long-Awaited Market Debut After ₹22,562-Crore IPO
-
 Explainer5 months ago
How Much SIP Do You Need to Build ₹1 Crore? The Power of Time and Compounding
-
 Podcast2 years ago
From ₹1 Lakh Lost to Managing ₹650 Crore: How Divam Sharma of Green Portfolio Built a Fundamental Investing Approach
-
 Podcast4 months ago
Can ₹200 SIPs Create India’s Next Investing Revolution? Ravi Kumar Jha’s Big Bet On Financial Inclusion
-
 Podcast1 year ago
From ₹1 Lakh Lost to Managing ₹650 Crore: How Divam Sharma of Green Portfolio Built a Fundamental Investing Approach
-
 News2 weeks ago
UPI Charges on Payments Above ₹2,000 Delayed Until After Diwali