Explainer
The Festive Sale Trap: Are You Really Saving Money or Just Spending More?

Every year around this time the banners go up. Big Billion Days. Great Indian Festival. Biggest sale of the season. The countdown clocks start ticking on your phone screen before you have even finished your morning chai and somewhere in your head a voice says: this is the week to buy.
These sales are expected to open in the same window this year, right before the festive season starts, just like they have for the last several years. For roughly a week the two platforms will throw everything they have at shoppers: flash deals, bank discounts, exchange bonuses and badges that scream up to 80% off. It is, by most accounts, the best week of the year to buy a phone, a television or a washing machine.
That contradiction sits at the heart of every festive sale season in India. The marketers are winning the game, no question. Whether the consumer is actually winning too is a far messier question and the honest answer is: it depends on how much homework you did before you clicked “buy now.”
The ₹1.2 lakh phone that becomes ₹99,999
Here is a scene that repeats itself on every sale day. A flagship phone is listed with an MRP of ₹1,20,000. During the festive sale it shows up at ₹99,999, a saving that looks like ₹20,000 straight into your pocket. The badge says 17% off. The urgency banner says only a few units left. It feels like a steal.
Except the phone was never really selling at ₹1,20,000 in the first place.
So the “discount” you are celebrating is partly real and partly an illusion built on a number that was inflated to begin with.
Brands and platforms know this works because human beings are wired to judge value by comparison rather than by an absolute number.
How the discount is actually decided
The math behind a festive sale price rarely starts with the question “what can we take off for the customer.” It usually starts somewhere else entirely.
Brands and platforms sit down months in advance and work backward from a margin target. A phone manufacturer wants to move old inventory before a new model launches. A platform wants to hit a gross merchandise value number that looks good in its next investor update. A bank wants more of its credit cards used during the festive quarter. All three sit at the same table and negotiate who absorbs how much of the “discount.”
Often the brand raises the base price a few weeks before the sale begins, then cuts it back down during the sale so the final number looks dramatic against the newly inflated one. Platforms add their own promotional coupons on top, funded partly by the seller and partly by the platform’s own marketing budget. Banks chip in an instant discount of 5 to 10 percent, capped at a fixed amount, in exchange for pushing their card to millions of shoppers who might not have applied for it otherwise. No cost EMI schemes are dressed up as free financing when in reality the “interest” is usually built quietly into the product price rather than charged separately.
Stack all of that together and the final number on your screen is not really a price. It is the output of a negotiation between four or five parties, none of whom were in the room to represent you.
How consumers end up fooled
None of this works without a few psychological nudges and Indian shoppers have gotten fairly familiar with most of them by now, even if they still fall for them.
Fake urgency is the most common one: “Only 2 left” or a countdown timer that resets the moment the sale extends by another day. Price history erasure is another, since most product pages show only the current price and the so called original one, never the actual trend over the past three months. Bundling dresses up value by throwing in an accessory or a subscription that inflates the perceived worth of the deal without meaningfully cutting the price of the product itself. Confirm shaming shows up in smaller ways too, in the guilt inducing pop up that appears when you try to close a cart or skip an add on, worded to make declining feel like a mistake.
India’s consumer regulator has actually put a name and a rulebook to a lot of this. The Central Consumer Protection Authority notified the Guidelines for Prevention and Regulation of Dark Patterns back in 2023, listing thirteen specific practices as unfair trade practices, including false urgency, drip pricing, basket sneaking and bait and switch. In 2025 the CCPA issued fresh advisories asking platforms to self audit and fined companies including an ed-tech major and a global security software firm for using manipulative design. More than two dozen major platforms have since submitted self declarations claiming to be free of these patterns, though the regulator has made clear that monitoring will continue regardless of what companies declare on paper.
The existence of a rulebook does not mean every seller follows it closely. It just means a shopper today has a name for the trick when they see it, which is more than they had a few years ago.
How to shop the sale without letting the sale shop you
None of this means festive sales are worthless. Genuine price drops do happen, especially on last generation electronics, home appliances nearing a model changeover, and fashion inventory that retailers simply need to clear before the next season. The trick is separating the real cuts from the theatre around them.
A few habits go a long way. Track the actual price of a product over the past two to three months rather than trusting the strikethrough MRP on the page, since several browser extensions and price tracking sites now do this for Indian marketplaces. Compare the same product across platforms and the brand’s own website before deciding, because the “biggest” sale badge does not always mean the lowest price on the internet that day. Read the fine print on no cost EMI offers and work out the flat price if you paid upfront, since the difference tells you how much interest is actually hiding inside the “zero cost.” And resist the countdown clock.
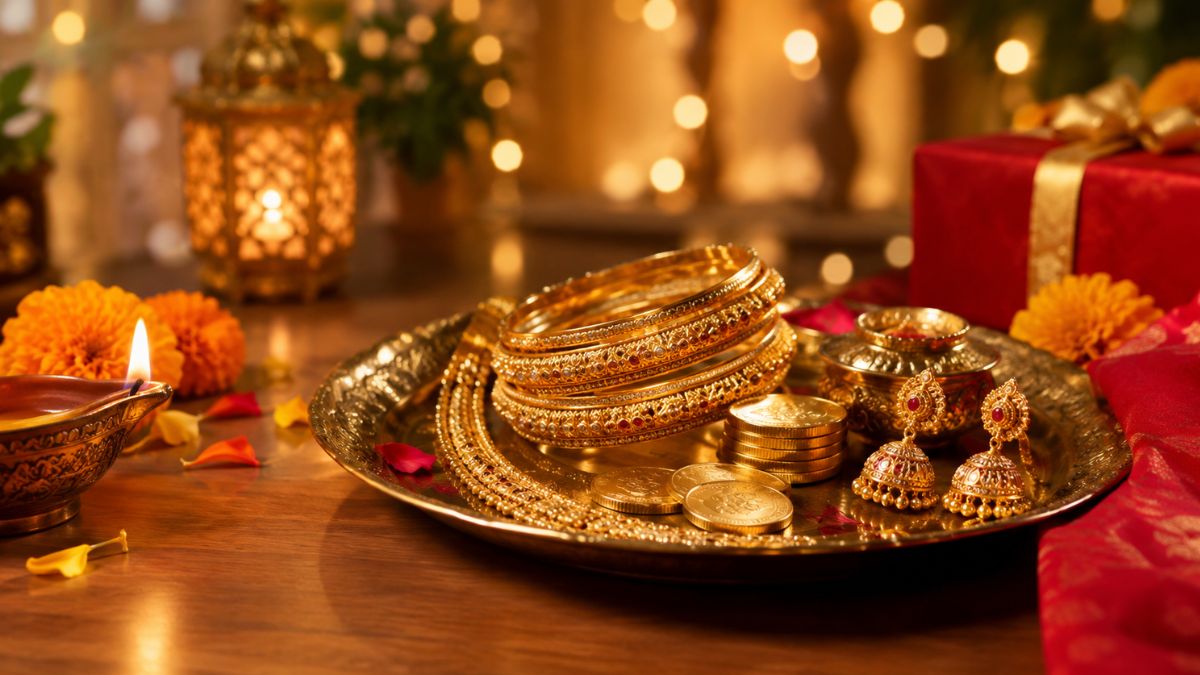
Every Diwali, many Indian families buy gold. For some, it is a small gold coin. For others, it is a new ring, a necklace or a piece of jewellery they have been planning to buy for months.
Dhanteras is considered an auspicious day to buy gold, and the tradition has been part of Indian households for generations. But with gold prices changing so much this year, one question is worth asking: Should you buy gold because it is Dhanteras, or because it makes sense for your money?
The answer depends on what you are buying, why you are buying it and how much you can comfortably spend.
Gold Prices Have Changed the Way People Shop
Gold prices have seen sharp ups and downs in 2026. After reaching record highs, prices have also fallen in recent weeks.
For buyers, this might seem like a good time to shop. But even after a price drop, gold can take a big bite out of a household’s budget.
This is also changing how people shop. Some are choosing lighter jewellery, while others are considering gold coins and bars instead.
But a lower price does not automatically mean gold is affordable for everyone. Even a small purchase can cost a significant amount.
The point is simple: just because gold prices have fallen does not mean you need to buy more.
Buying Gold and Investing in Gold Are Not the Same Thing
For many families, buying gold is part of celebrating Diwali. It could be jewellery for a wedding, a gift for a loved one or simply a way to keep a family tradition alive.
There is nothing wrong with that.
But buying jewellery and investing in gold are two different things.
When you buy jewellery, you pay for more than just the gold. The final bill also includes making charges, which cover the work that goes into creating the piece, along with applicable taxes.
And if you decide to sell the jewellery later, you may not get back the full amount you spent. Making charges, for example, may not be returned.
So, even if gold prices rise, your jewellery may not give you the same return.
If you are buying jewellery to wear, enjoy it. If you are buying gold to grow your money, compare your options first.
Should You Buy Gold Now or Wait?
This is a question many people ask before Dhanteras.
Gold prices can change for several reasons, including global events, interest rates and changes in the value of the rupee. This makes it difficult to predict whether prices will rise or fall in the coming weeks.
Trying to find the perfect time to buy can become stressful, especially if you need gold for a wedding or a family occasion.
If you already know you want to buy gold, start by deciding how much you can spend. You could also consider buying in smaller amounts over time instead of trying to predict the lowest price. This does not guarantee a better deal, but it can help you avoid depending on a single day’s price.
And if the purchase is not urgent, there is no need to rush just because Dhanteras is around the corner.
Gold Jewellery, Coins or Gold ETFs: What Should You Choose?
There is more than one way to buy gold. The right choice depends on what you want from it.
Gold jewellery: If you want something to wear or gift, jewellery makes sense. Just remember to check the making charges and the final bill.
Gold coins and bars: These let you own physical gold without paying for an elaborate jewellery design. However, there may still be additional purchase costs. You should also check how easy it will be to sell them later.
Gold ETFs: These allow you to invest in gold through the stock market without storing physical gold. You generally need a demat and trading account, and there are costs and market risks to consider.
None of these options is the best choice for everyone. If you want gold to wear, jewellery may be right for you. If you want to invest, compare the costs and risks before deciding.
And remember, gold prices can fall too. Do not put all your savings into gold or use money you may need for emergencies.
Before You Buy Gold This Dhanteras, Ask Yourself Three Questions
Before heading to the jewellery store, take a moment to ask yourself three simple questions.
1. Can I afford this without borrowing?
Decide your budget before you shop. Avoid using your emergency savings or taking on expensive debt just to follow a festive tradition.
2. Am I buying it to wear or to invest?
Both are valid reasons. Knowing why you are buying gold can help you choose the right option.
3. Have I checked the final price?
Check the gold rate, purity, making charges and applicable taxes. Ask about the jeweller’s exchange and buyback rules, too.
A few simple checks can help you avoid surprises later.
Celebrate the Festival. Keep Your Finances in Mind.
Dhanteras is a time to celebrate prosperity, and buying gold can be a meaningful part of that celebration.
But being financially secure is about more than what you bring home from a jewellery store. It is also about the savings you build, the debt you avoid and the goals you work towards.
You do not have to spend a large amount to celebrate the festival. And you do not have to buy gold just because everyone else is doing it.
This Dhanteras, buy gold if it makes sense for you. Just make sure your budget decides how much you spend, not the occasion.
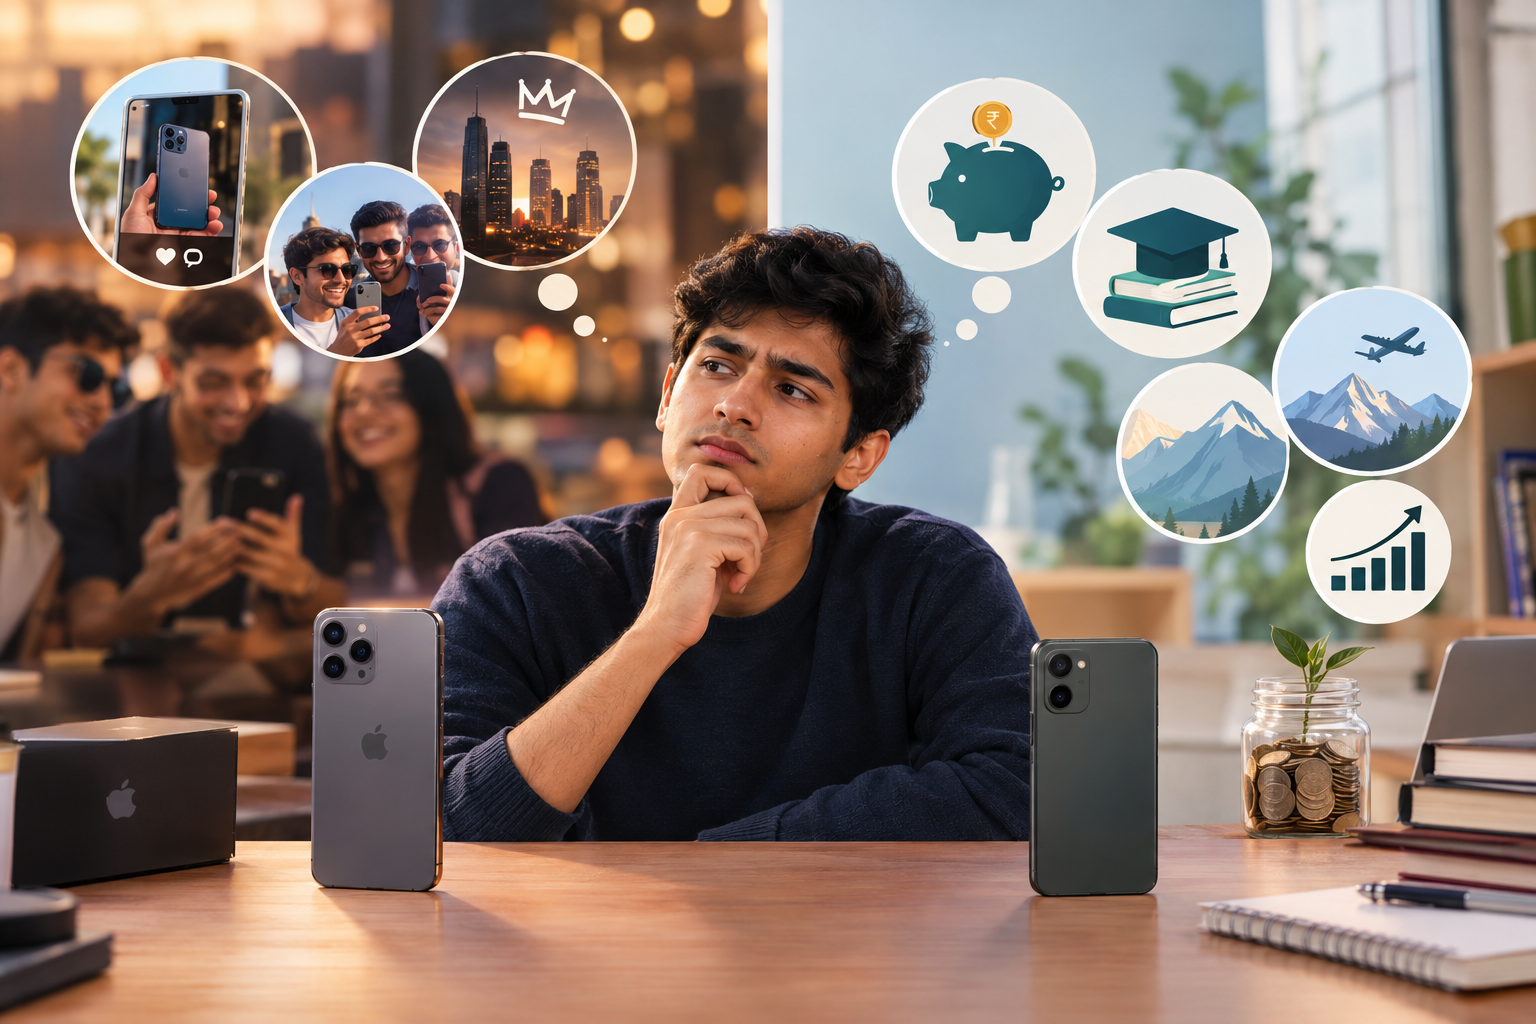
For young earners, buying an expensive smartphone can feel like a reward for hard work. But when does the desire to look successful start getting in the way of building wealth?
The first salary brings a new kind of freedom. A young professional can finally buy things without asking for money. And often, the first big purchase is a smartphone.
Friends are flaunting their latest devices, Instagram is flooded with unboxing videos and a perfectly functional phone suddenly feels outdated. An ₹80,000 smartphone starts looking less like an expense and more like a reward for all the hard work.
But there is a difference between buying something because it adds value and buying it because it makes life look better to others.
India’s premium smartphone obsession
India’s smartphone market is moving towards premium devices. According to Counterpoint Research, smartphones priced above ₹30,000 accounted for 22% of smartphone shipments in India in 2025, their highest ever share.
A July 2026 Counterpoint Research survey also found that 46% of prospective smartphone buyers in India were willing to stretch their budgets to purchase their preferred phone despite price increases. Among consumers aged 25 to 30, the figure was 52%.
These numbers do not mean everyone buys expensive phones for status. Better cameras, performance and software support can justify the premium. However, they highlight how willing consumers can be to spend beyond their original budgets for a device they desire.
For young professionals still building their savings, this creates a dilemma: should the money go towards a premium phone or towards financial security?
What does an ₹80,000 phone actually cost?
Consider someone earning ₹40,000 a month and choosing between a ₹15,000 smartphone and an ₹80,000 device.
The premium phone costs twice their monthly salary before deductions. The budget alternative costs less than half of one month’s salary.
The difference is ₹65,000. That money could help build an emergency fund, pay for professional training or contribute towards future investments.
Of course, a premium phone may offer better features and a longer useful life. The point is not that expensive phones are always a bad purchase. It is whether the additional benefits justify the additional cost.
The EMI trap
Monthly instalments can make an expensive purchase feel manageable. Instead of thinking about ₹80,000, buyers focus on a smaller monthly payment.
But an affordable EMI does not automatically make a purchase financially sensible.
If repayments leave little money for savings, rent or other priorities, the phone may be stretching the budget more than it appears. Interest and fees can also increase the total cost.
The real cost of keeping up
The phone that attracts compliments today may become ordinary tomorrow. A newer model arrives, attention shifts and the excitement fades. The money spent, however, does not return.
For someone whose main motivation is social recognition, this creates an uncomfortable trade off. The owner bears the full cost while the approval may last only a short time.
Choosing a budget phone and keeping the ₹65,000 difference could create room for savings, experiences or investments. For illustration, ₹65,000 invested at an assumed annual return of 10% could grow to approximately ₹1.05 lakh over five years, before taxes and charges. Actual returns are not guaranteed.
So, should young earners buy budget phones?
Not necessarily. A premium phone can be worth the money when its features genuinely matter and the purchase fits comfortably within the buyer’s finances.
But before upgrading, it helps to ask: is the phone being purchased for its usefulness or because everyone else seems to have one?
Affordable smartphones have expanded the choices available to consumers. For everyday needs such as messaging, digital payments, browsing and streaming, a budget device may be sufficient.
A smartphone can signal purchasing power, but it cannot tell anyone how financially secure its owner really is.
The real flex is not owning the most expensive phone. It is being able to afford the things that matter without sacrificing the financial freedom that makes them possible.
There was a time when buying a designer bag was fairly straightforward: you liked it, you could afford it, and you bought it.
Now, things are a little different.
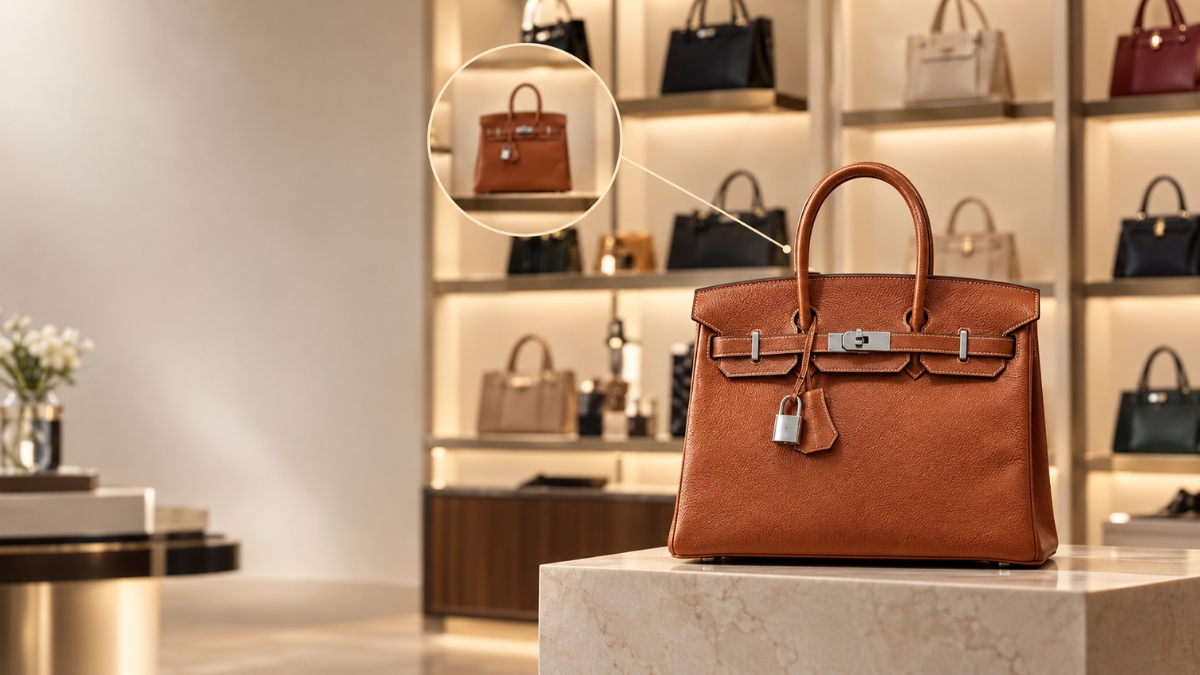
People are booking appointments, joining waitlists and hunting down specific colours, materials and limited-edition pieces. There are collectors with entire rooms dedicated to their handbags. And increasingly, buyers aren’t looking at these bags only as fashion purchases; they are looking at what the bag could be worth years down the line.
That got me thinking: when did a handbag start looking like an investment?
The Numbers Are Making The Case
According to the Knight Frank Luxury Investment Index, handbags were the best-performing luxury collectible category in 2024, gaining 2.8%.
Economic Times also highlighted how certain luxury handbags can sell for significantly more in the resale market than their original retail price. One example cited was an Hermès Birkin 25, which retailed at around ₹10.2 lakh but was selling for roughly ₹18 lakh in the resale market.
That’s a pretty interesting premium for something that is technically still a handbag.
Forbes has been making a similar argument for years. Its research has looked at designer handbags particularly sought-after Hermès pieces as an alternative investment, comparing their appreciation with traditional luxury assets such as art.
Of course, that doesn’t mean your wardrobe is suddenly a stock portfolio. But it does show that something interesting is happening in the luxury market.
Scarcity Is Doing A Lot Of The work
The most valuable handbags aren’t necessarily the most expensive ones. They’re often the ones people can’t easily get.
Limited production, discontinued designs, rare colours and materials, celebrity associations and strong brand demand can all contribute to resale value.
And that explains the waitlists.
The scarcity itself becomes part of the product. If everyone could walk into a store tomorrow and buy the same bag, some of that exclusivity and potentially some of its resale appeal would disappear.
It’s the same basic idea we see with many collectibles: when supply is limited and demand stays strong, people are willing to pay more.
This Is Also Creating A New Kind Of Collector
There are serious collectors building entire portfolios of handbags. Some buy specific models because they believe they will hold their value. Others look for pieces that are rare or difficult to find.
And yes, there are people whose collections are large enough to require dedicated storage.
At that point, we’re moving beyond fashion. We’re talking about an asset that someone is deliberately acquiring, preserving and potentially reselling.
And Then There’s The Collateral Angle
Here’s where things get even more interesting.
In some markets, specialist lenders allow owners to borrow against valuable luxury handbags, using them as collateral. In simple terms, the bag is valued and the owner can potentially access a loan against that value.
But this is where one should draw the line between “valuable asset” and “investment.”
Not every designer bag will qualify. And not every bag will be appreciated. Brand, model, condition, authenticity, rarity and resale demand can all influence its value.
So, are designer bags actually investments?
Sometimes. But not every expensive handbag is an investment. A stock can generate dividends. A bond can generate interest. A property can generate rent. A handbag doesn’t do any of that.
Its investment potential comes from what someone else may be willing to pay for it later. And that makes the market much more dependent on trends, scarcity and consumer demand.
So yes, a ten lakh handbag could potentially become more valuable over time.
But that doesn’t mean spending ten lakh on a handbag is automatically a smart financial decision. The smarter way to look at it may be this: a designer bag can be a luxury purchase that happens to have investment potential, not an investment that happens to be a bag.
-
 News4 weeks ago
SC Says No Stay On New UPI Charges Above ₹2,000
-
 Podcast1 year ago
Nitin Jain: From IIT to Investment Titan, Managing ₹60,000 Crore AUM
-
 News1 month ago
NSE Makes Long-Awaited Market Debut After ₹22,562-Crore IPO
-
 Explainer5 months ago
How Much SIP Do You Need to Build ₹1 Crore? The Power of Time and Compounding
-
 Podcast2 years ago
From ₹1 Lakh Lost to Managing ₹650 Crore: How Divam Sharma of Green Portfolio Built a Fundamental Investing Approach
-
 Podcast4 months ago
Can ₹200 SIPs Create India’s Next Investing Revolution? Ravi Kumar Jha’s Big Bet On Financial Inclusion
-
 Podcast1 year ago
From ₹1 Lakh Lost to Managing ₹650 Crore: How Divam Sharma of Green Portfolio Built a Fundamental Investing Approach
-
 News2 weeks ago
UPI Charges on Payments Above ₹2,000 Delayed Until After Diwali