Podcast
From ‘Nimbu Pani’ to ‘Narasimha Avatar’: Lakshmi Iyer’s Guide to the ‘Decadal Journey’ of Investment
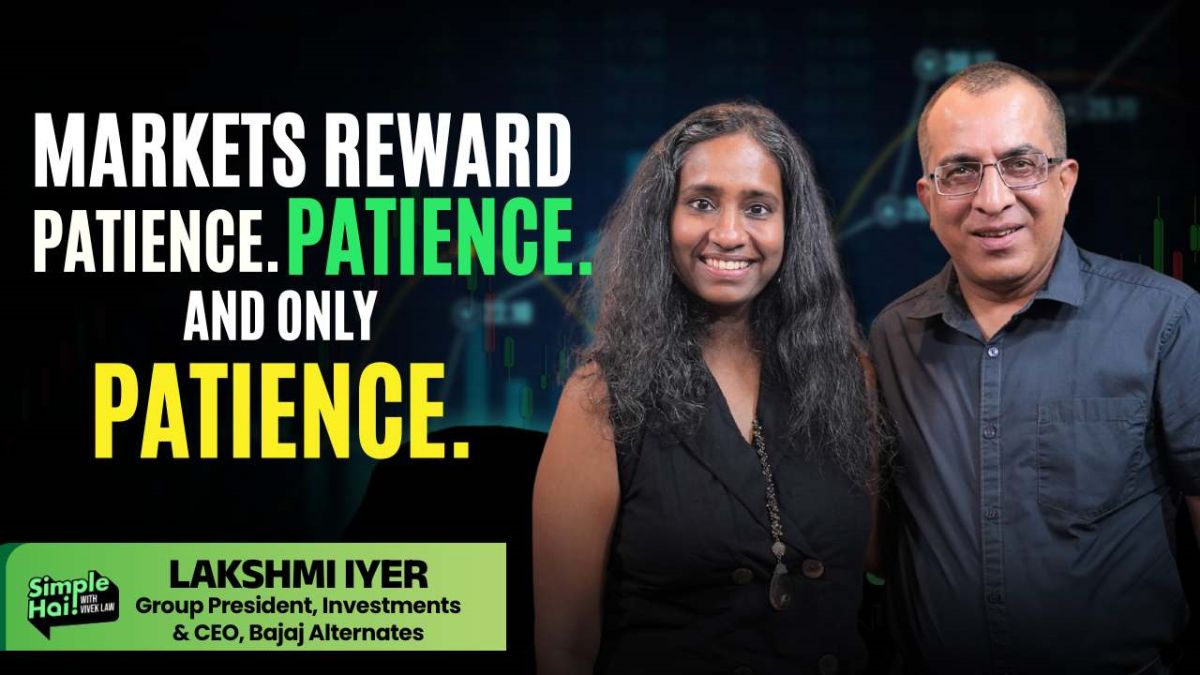
Lakshmi Iyer, Group President, Investments and CEO of Bajaj Alternates, explains why wealth creation is a ‘decadal journey’ that rejects instant gratification, highlights the ‘Cinderella treatment’ of debt, and argues that the evolution of the Indian investor is a ‘non-negotiable’ shift driven by a ‘Digical’ ecosystem on Simple Hai!, the financial podcast hosted by Vivek Law.
Iyer describes her professional philosophy as “Go with the Flow,” often comparing herself to water that adapts to the shape of its container. For her, direction matters far more than rigid planning. Drawing a reference from Vidya Balan’s The Dirty Picture, she says that while the film industry thrives on “Entertainment, Entertainment, Entertainment,” the investment world survives on “Patience, Patience, Patience.” According to Iyer, many people forget that wealth creation is a decadal journey rather than a process measured in weeks, months, or even a few years.
Just as a plant requires water, nourishment, and sunlight to grow into a tree, investments also need time and consistent attention. Iyer points out that many mutual fund schemes have delivered returns that outperformed benchmarks over 20- or 30-year periods. However, very few investors stay invested long enough to experience those long-term benefits.
She believes that one of the biggest obstacles to successful investing is the modern culture of instant gratification. Social media has conditioned people to seek immediate rewards through likes, comments, and constant validation, creating a dopamine-driven mindset that often spills over into financial decisions. According to Iyer, investors must honestly ask themselves whether they are giving their investments enough time to grow.
Debt: The All-Seasons Footwear
Iyer challenges the common perception that mutual funds are only about equities. She argues that debt deserves a much more significant place in an investor’s portfolio.
She compares debt investments to lemonade or “nimbu pani,” describing them as an all-season asset class that provides stability regardless of market conditions. Unlike equities, debt investments offer multiple options, allowing investors to remain invested for as little as one day or as long as 10 years.
On the other hand, she describes equity as the “caffeine” or “energiser” of a portfolio. Equities provide growth and can potentially double capital over five to seven years, while debt acts as the stabilising force that protects emergency and contingency funds.
Why Does Gold Deserve the ‘Narasimha Avatar’ Label?
Using mythology to explain investment behaviour, Iyer compares gold to Lord Vishnu and says that the precious metal has recently assumed the “Narasimha Avatar” because of its sharp rise in value.
According to her, increasing investment demand and central banks’ growing purchases of gold have fuelled this rally. She believes declining confidence in paper currency has also contributed to the trend.
However, she warns investors against expecting extraordinary returns from gold forever. Instead, she recommends maintaining a 10-15% allocation to gold, primarily as a portfolio-balancing asset.
At the same time, she argues that fixed-income investments often receive the “Cinderella treatment” from both investors and the media. Traditional products such as fixed deposits continue to dominate public perception, despite debt investments offering several advantages. She also explains that interest rate cuts generally have a positive impact on fixed-income returns because of their inverse relationship.
Is India Still in the ‘Intermission’ Phase of Investing?
According to Iyer, India is currently in the “intermission” stage of its transition from a nation of savers to a nation of investors.
She compares this transformation to a caterpillar becoming a butterfly and insists that this shift is non-negotiable for long-term financial well-being.
For new investors, her advice is simple: start today. She strongly believes that “time in the market” is significantly more important than “timing the market.”
Although financially aware individuals can manage investments independently, she believes most people should seek professional guidance without hesitation. Financial advisors, she argues, provide customised services and deserve to be compensated rather than being expected to offer free advice.
What Is the ‘Digical’ Future of Investing?
Looking ahead, Iyer believes the future of investing will be “Digical”—a combination of digital technology supported by a physical human connection.
She explains that technology has dramatically improved accessibility and convenience, particularly in alternative investments, much like infrastructure projects such as the Mumbai Coastal Road have transformed transportation.
According to her, the financial ecosystem should focus on collaboration rather than competition. Referencing the film Teri Baaton Mein Aisa Uljha Jiya, she highlights how technology is rapidly blurring the boundaries between human and machine interactions.
Why Is the Alternates Industry Generating So Much Excitement?
Iyer says her decision to lead Bajaj Alternates was driven by her desire to embrace new challenges.
She describes the alternatives industry as a “toddler” compared with the “adult” mutual fund industry, estimating that alternatives are currently where mutual funds were 10-15 years ago.
Because of its relatively small size, she believes the sector has enormous growth potential, with expected growth rates of 20-30% annually. Alternative investments also provide greater flexibility by allowing investors to combine public and private assets, along with equity and fixed-income investments.
However, she cautions that products such as private equity, which focus on unlisted companies, carry higher levels of risk despite offering the potential for higher returns. She compares the experience to the adrenaline rush of bungee jumping.
Iyer concludes with one of the most important financial lessons she learned from her parents: never spend more than you earn. She warns against excessive borrowing, particularly when people fail to understand the true cost of debt, reminding investors that financial discipline remains the foundation of long-term wealth creation.
Podcast
Gold Loans, MSME Credit and Digital Lending: Rakesh Singh on India’s Changing Borrowing Habits
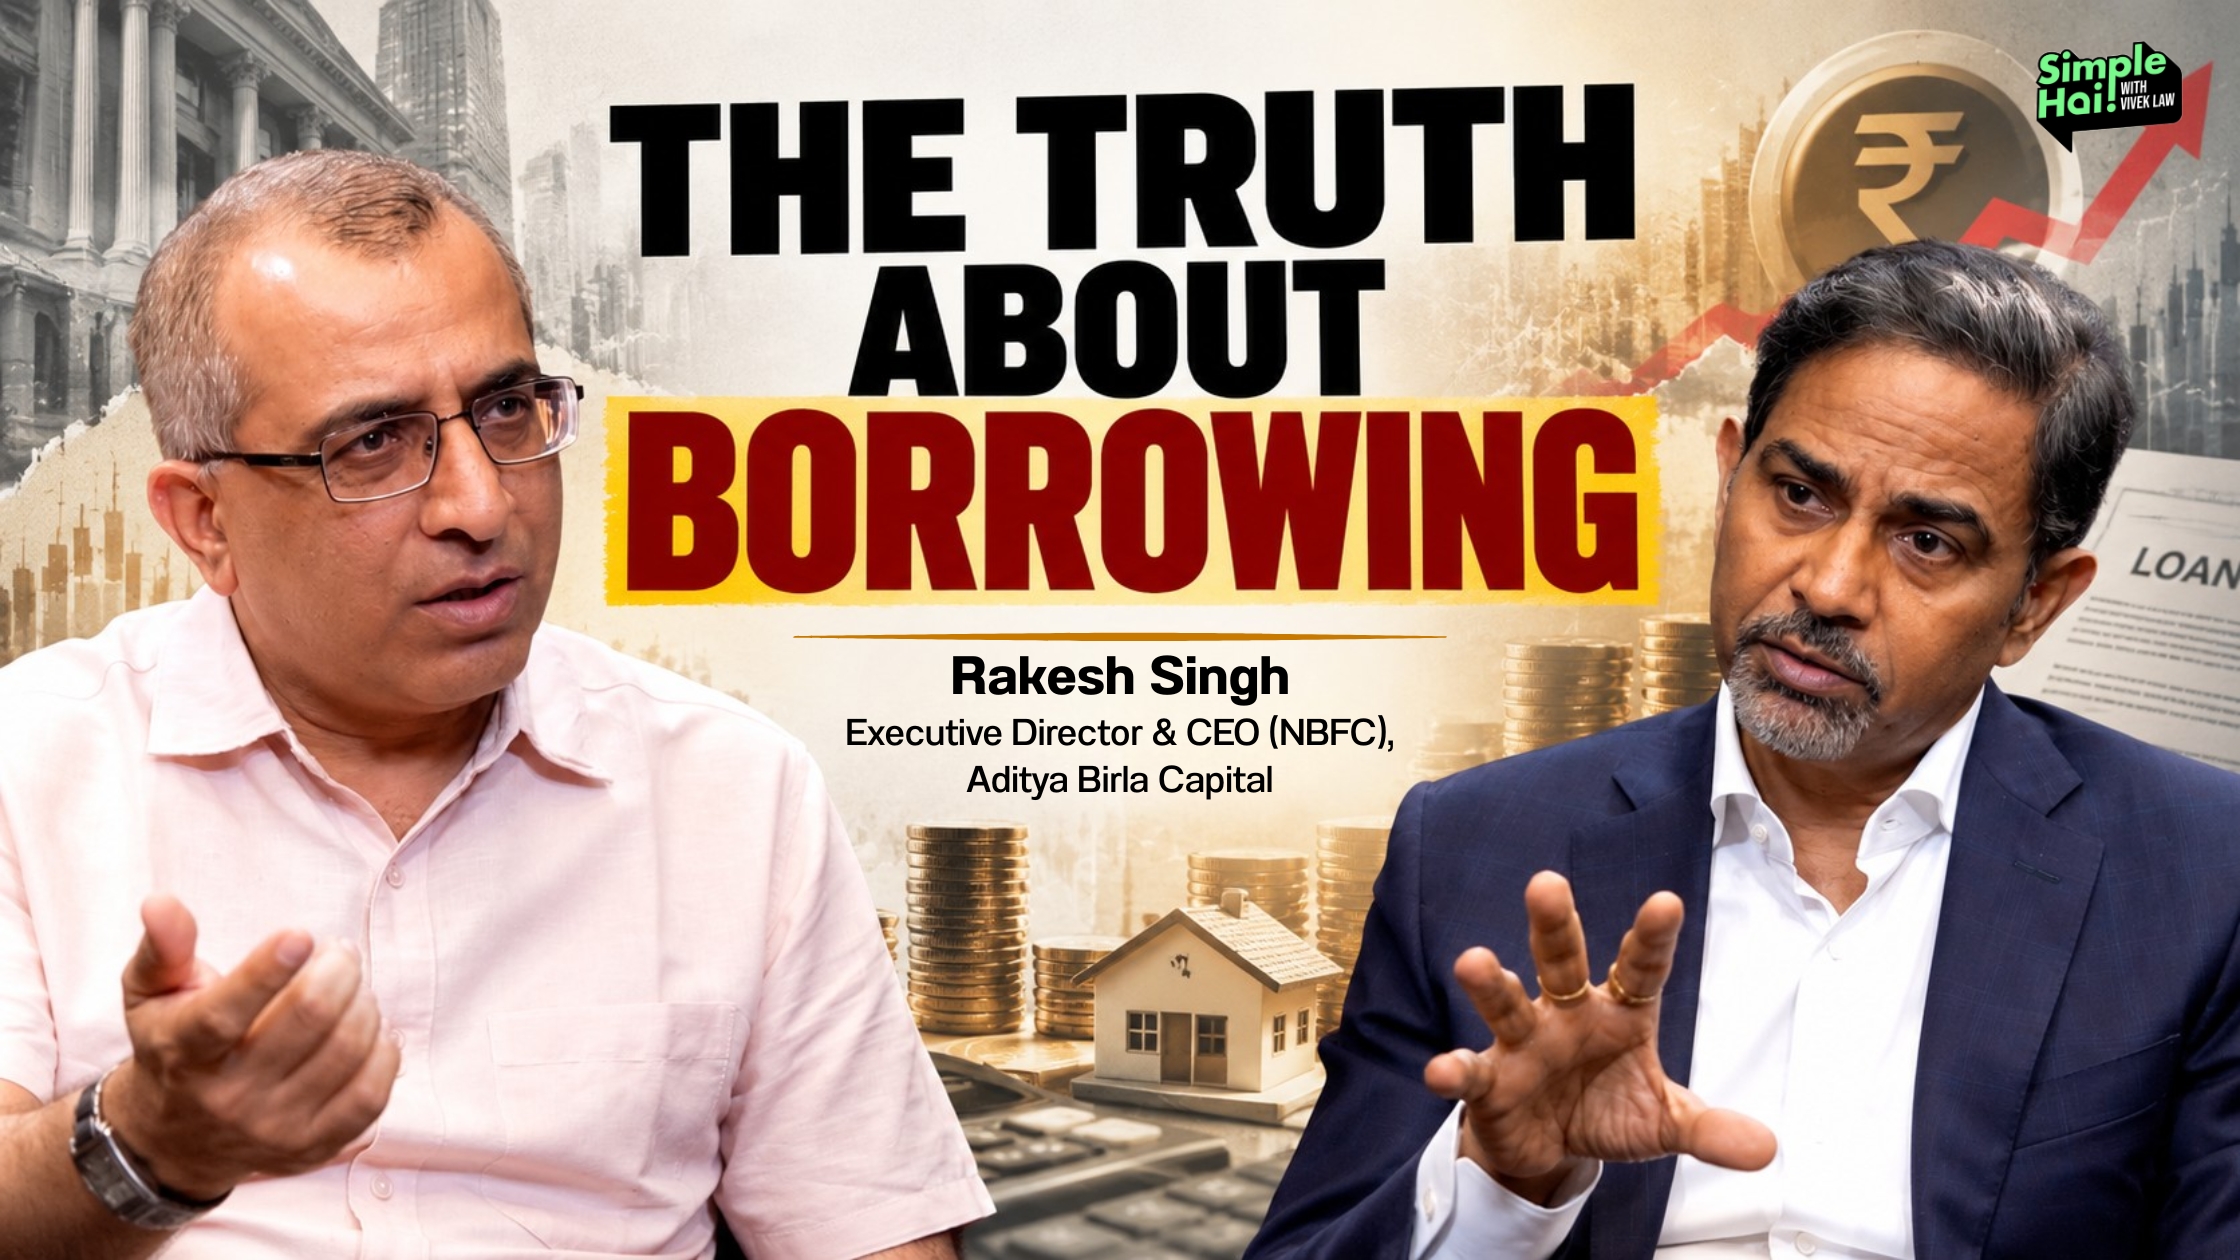
India’s lending landscape is evolving as technology makes credit more accessible and businesses look for faster ways to raise funds. From households using gold as collateral to small businesses seeking formal credit, borrowing is becoming an important part of how individuals and enterprises manage their financial needs.
In a conversation with Vivek Law on The Simple Hai! Show, Rakesh Singh, Executive Director and CEO (NBFC) at Aditya Birla Capital, discussed the growth of gold loans, the credit gap faced by micro, small and medium enterprises (MSMEs), the role of digital platforms in lending, and why responsible borrowing must remain a priority.
Gold Loans: Putting Household Savings to Productive Use
Gold has traditionally been an important form of savings for Indian households. Singh noted that Indian families collectively hold an estimated $5 trillion worth of gold, presenting a significant opportunity for the gold loan market.
According to Singh, the gold loan industry has grown considerably over the past two to three years, partly because rising gold prices have increased the value of the collateral borrowers can offer. He cited an industry size of around ₹19 lakh crore, with NBFCs accounting for approximately ₹4 lakh crore and banks making up the remainder.
Gold loans can help people access funds without selling family jewellery. Singh explained that borrowers often use these loans to invest in their businesses or pay for their children’s education, making them a source of funds for specific financial needs rather than everyday consumption.
He also highlighted the potential in semi-urban and rural areas, as well as Tier 3 and Tier 4 markets, where access to such lending products can expand further.
Trust Is Key to the Gold Loan Business
Borrowing against gold involves more than a financial transaction. For many families, jewellery carries emotional and generational value, making trust an essential part of the process.
Singh said established brands can help customers feel more confident about pledging their gold. Transparency, responsible handling of jewellery and a customer-first approach are important to building that confidence.
He also pointed to a geographical shift in the market. While gold lending was previously concentrated in southern states, Singh said growth is increasingly visible in northern, eastern and central India, including markets such as Delhi-NCR, Uttar Pradesh and Rajasthan.
For Aditya Birla Capital, entering this segment is an opportunity to expand its lending presence across the country while focusing on customer trust and responsible growth.
MSMEs Continue to Face a Credit Gap
Access to formal credit remains a challenge for many small businesses. Singh observed that some MSMEs continue to borrow from friends, family or local sources, sometimes at significantly higher rates, because they cannot easily access suitable formal financing.
He said banks, NBFCs and fintech companies each have a role to play in addressing this gap. Rather than simply competing with one another, these institutions need to reach different customer segments and offer products suited to their requirements.
Speed is another important factor. For a small business, delays in accessing funds can affect day-to-day operations and growth plans. Lenders therefore need to combine appropriate credit assessment with efficient processes.
Singh also shared that approximately 57–58% of Aditya Birla Capital’s loan book, which he referred to as around ₹1.70 lakh crore during the discussion, was directed towards MSMEs.
How Digital Platforms Are Changing Lending
Digital infrastructure is making it easier for lenders to assess small businesses that may previously have had limited access to formal credit.
Singh highlighted the role of digital payments, Aadhaar-based verification, PAN linkages, GST records and credit bureau information in helping lenders understand customers and their financial activity. As more businesses use digital payment systems, lenders can gain a clearer picture of their transactions and banking behaviour.
Aditya Birla Capital developed its Udyog Plus digital platform to serve MSMEs. Singh said the platform had close to 2.4 million registered businesses at the time of the conversation.
Through digital processes, some smaller loans can be assessed, approved and disbursed within minutes. Larger or more complex applications may still require intervention from branches and credit managers.
Digital platforms can also help businesses access services beyond financing, including support related to accounting and human resources.
Digital Lending Must Be Matched With Responsible Borrowing
Technology has made it easier for customers to access credit, including through digital platforms and financing options offered during online purchases. However, Singh cautioned that easier access to loans also brings risks.
When customers take multiple loans from different lenders, their overall debt burden can rise. Singh stressed that lenders need to monitor a borrower’s leverage not just when approving a loan, but also after the money has been disbursed.
For borrowers, understanding repayment capacity is equally important. People should assess how much they can repay, when their income is likely to arrive and whether the repayment schedule suits their financial circumstances. This can be particularly important for those with irregular or seasonal earnings.
Singh also emphasised the importance of awareness around credit scores and repayment discipline. Delayed payments can affect a borrower’s credit record and future access to loans.
The Future of Lending Depends on Access and Awareness
India’s growing economy, expanding digital infrastructure and changing borrowing needs are creating opportunities for lenders. Gold loans can help households unlock funds against an existing asset, while better access to formal credit can support small businesses.
But greater access alone is not enough. As Singh explained, lenders must understand the customer segments they serve, manage risks carefully and ensure that credit reaches borrowers whose needs and repayment capacity align with the product.
For borrowers, the message is equally clear: a loan should serve a financial purpose, and taking one should always involve a clear understanding of its cost and repayment obligations.
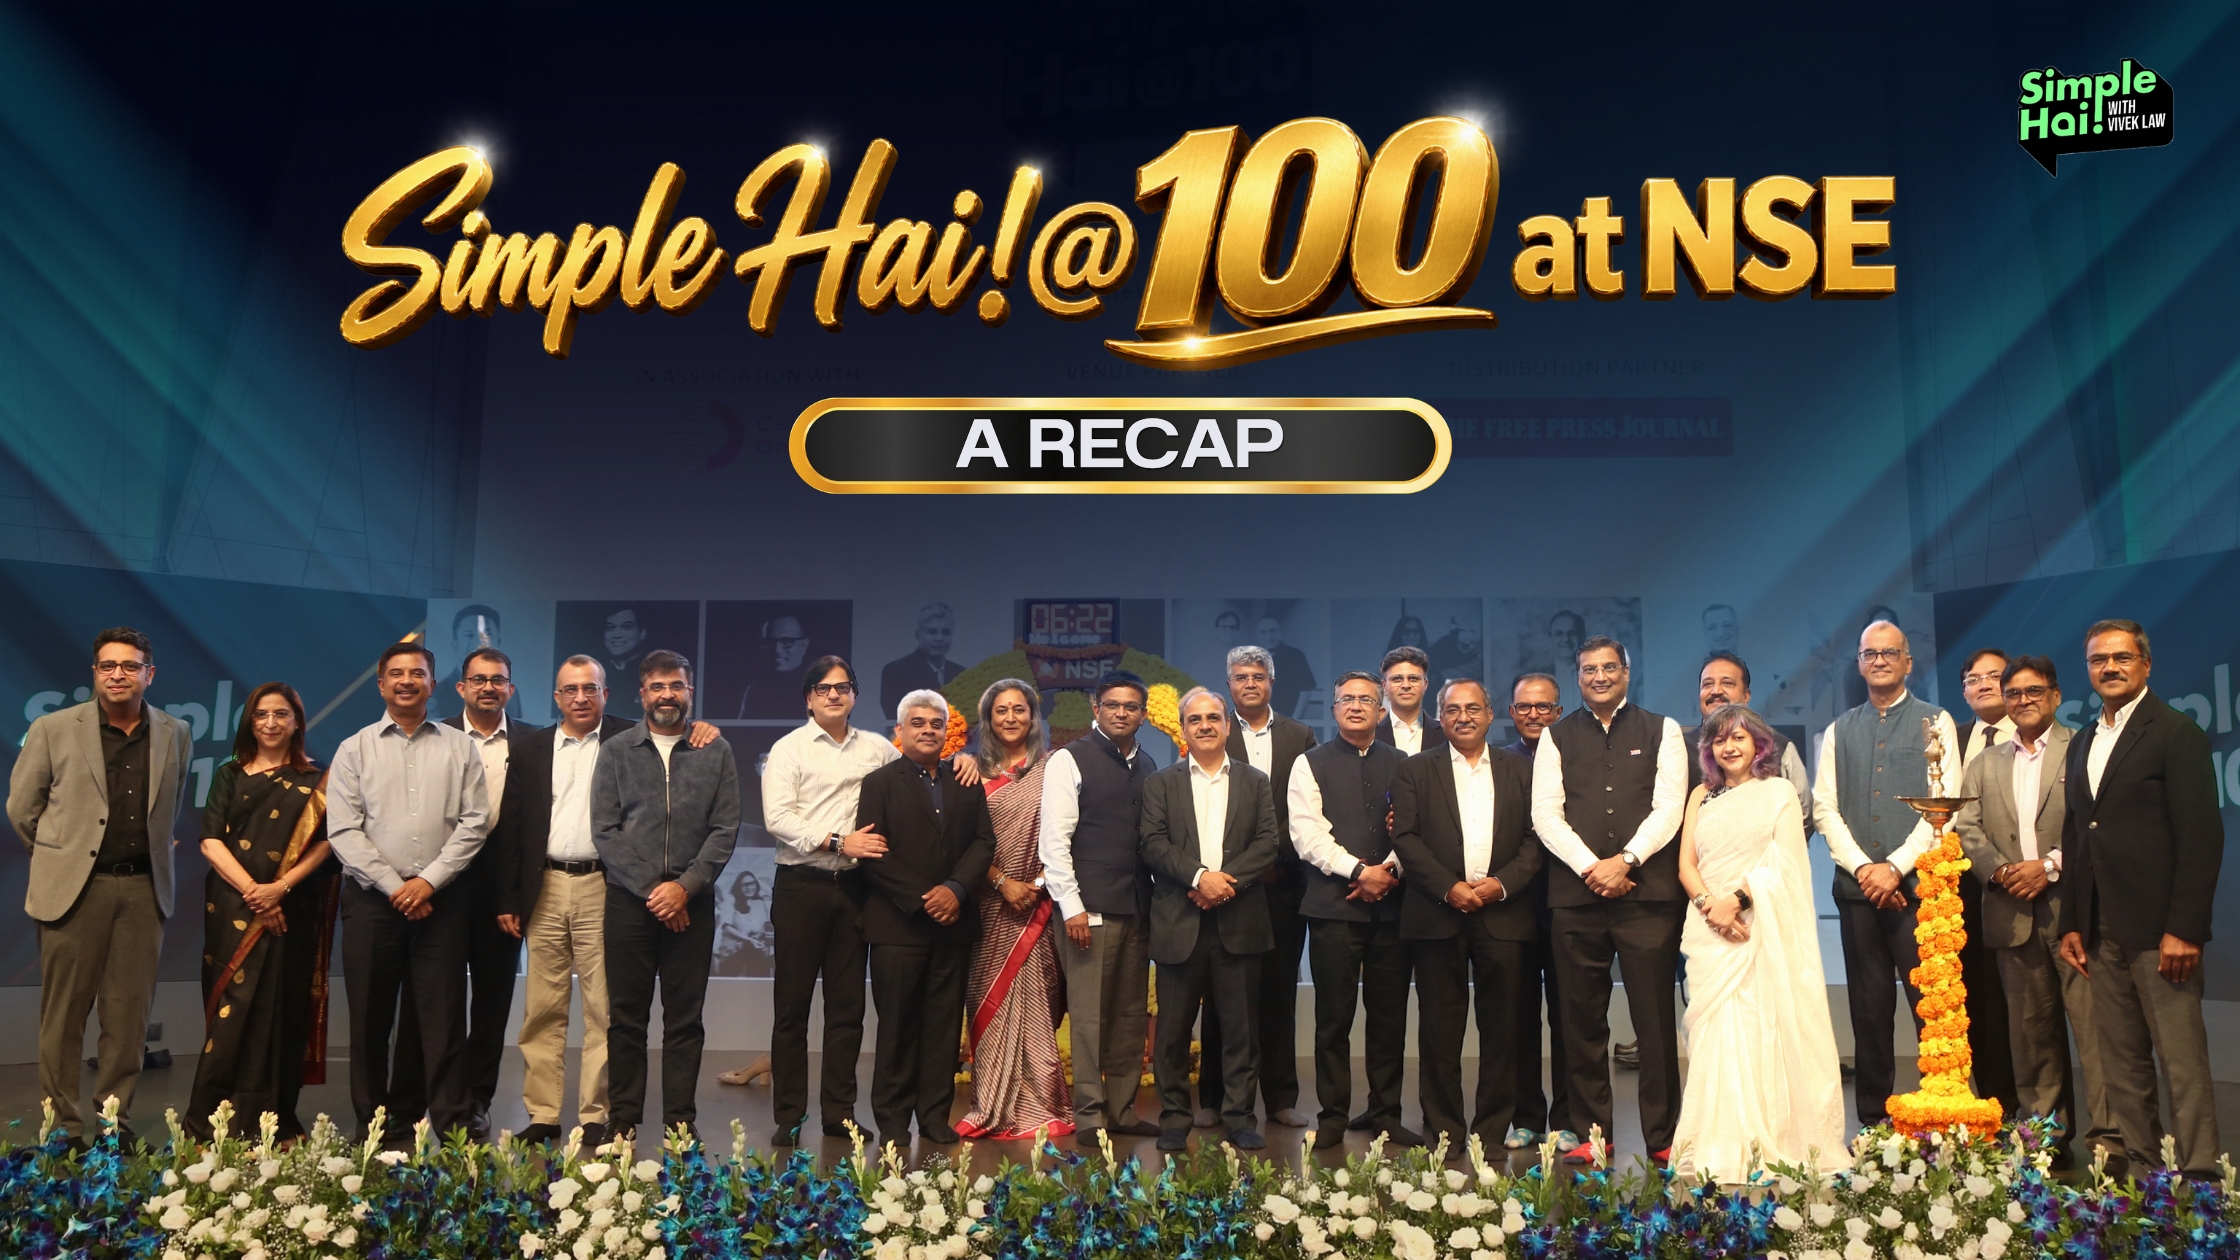
From financial awareness to financial confidence, Simple Hai! marks 100 episodes with a celebration of conversations, learning and the people behind the journey. A hundred episodes is more than a number. For Simple Hai!, it represents years of conversations aimed at making money easier to understand. The milestone was celebrated with the Simple Hai! @ 100 event, bringing together the people who have shaped, supported and powered the show. The celebration reflected on the journey of building a financial education platform around one simple idea: finance does not have to feel complicated.
From Awareness To Confidence
Over its journey, Simple Hai! has explored subjects ranging from investing and wealth creation to retirement planning and everyday money decisions.
The show’s conversations have also reflected how India’s financial landscape has changed.
Mutual funds, investing and personal finance have become more accessible to younger audiences. Digital platforms have further changed how people learn about money.
The show has reached audiences beyond India’s major metros, with viewers across more than 15 countries.
It has also crossed 38 million impressions and nearly 5 million views, reflecting the growing demand for accessible financial education.
The People Behind Simple Hai!
The celebration also recognised the team working behind the camera.
Co-founders Aparna Joshi, Harish Patil and Deepak Karna joined Law during the event, highlighting the collaborative effort behind the platform.
The wider OneNative Studio team was also brought on stage as part of the celebration.
That moment reinforced an important part of the show’s journey.
A finance platform may have a host at the centre, but building 100 episodes requires researchers, producers, editors, designers and everyone working behind the scenes.
A Conversation With Ashishkumar Chauhan
Ashishkumar Chauhan, MD and CEO of the National Stock Exchange, also joined the celebrations through a conversation and message recognising the milestone.
He highlighted the role of financial media in making investment conversations more accessible.
The discussion also looked at how Indian investors have changed over the years.
Law recalled a time when mutual funds were far less familiar to ordinary investors. Today, financial products and investment information are significantly more accessible.
The challenge has consequently shifted from access to understanding.
The Philosophy Behind The Show
One recurring idea from the celebration was the importance of knowledge.
A story from India’s financial markets captured that philosophy particularly well.
Veteran brokers once suggested that while people may worship Lakshmi, the goddess of wealth, they should remember Saraswati, the goddess of knowledge, every day.
For Simple Hai!, that idea fits the journey.
Financial confidence cannot come only from having access to products. It also requires knowledge, discipline and the confidence to ask questions.
What’s Next For Simple Hai!?
Reaching 100 episodes is being treated as a milestone rather than a finish line.
The platform plans to explore artificial intelligence and other technologies to make financial education more accessible.
The newly launched Simple Hai! website will also bring together its podcasts and financial education content.
As the show enters its next phase, its central promise remains unchanged.
Make finance simpler. Make financial conversations more accessible. And help more Indians become confident with their money.
For Simple Hai!, 100 episodes are therefore less about looking back and more about asking what comes next.
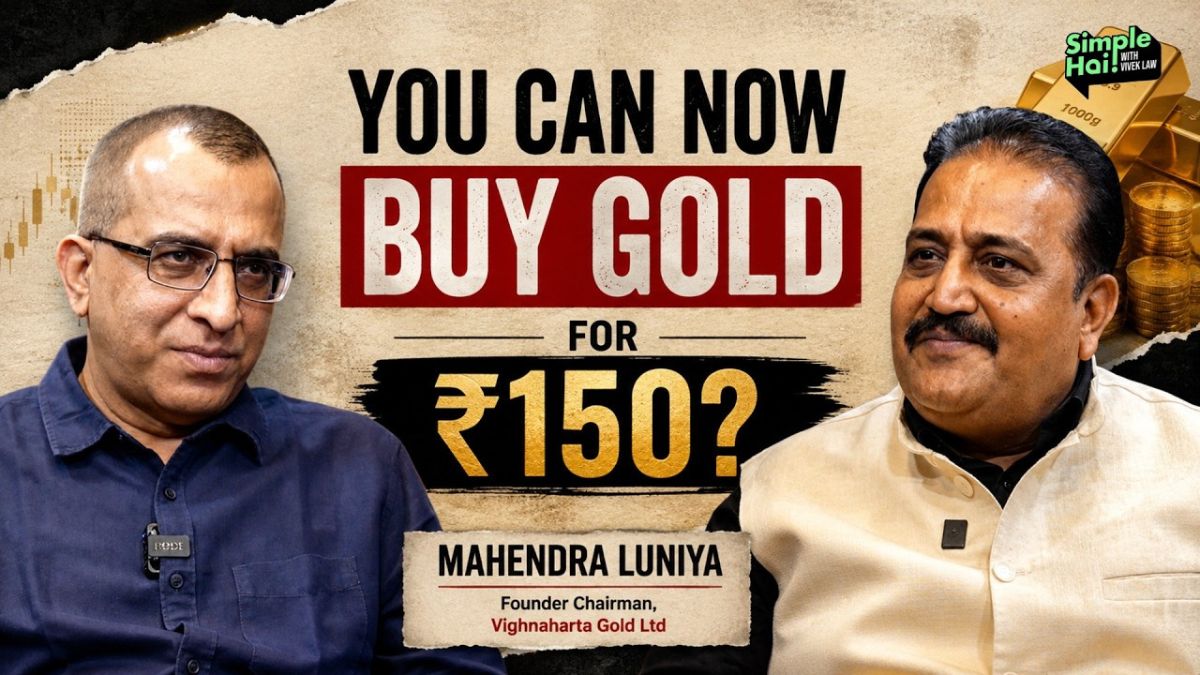
Gold has long been India’s preferred store of wealth. It is bought during festivals, gifted at weddings and passed down through generations. But while Indian households continue to accumulate the precious metal, much of it remains locked away in lockers, generating little economic value.
According to Mahendra Luniya, Founder Chairman, Vighnaharta Gold Ltd., this vast stockpile of household gold represents one of India’s biggest untapped economic opportunities. Speaking on the Simple Hai! podcast hosted by veteran business journalist Vivek Law, Luniya argued that digitising gold ownership and bringing idle gold into the formal financial system could unlock liquidity, reduce import dependence and reshape how Indians invest in the precious metal.
Gold Goes Digital
Luniya compared the evolution of gold ownership to the transformation witnessed in equity markets and payments over the last two decades.
“Shares moved from paper certificates to demat accounts. Cash moved from wallets to UPI. Gold is now following the same path,” he said.
With prices touching around ₹1.5 lakh per 10 grams, purchasing physical gold has become increasingly expensive for many households. Digital platforms, however, allow investors to start with significantly smaller amounts.
“You can now buy gold for as little as ₹150,” Luniya said, adding that digital ownership makes regular investing possible, much like a systematic investment plan (SIP). Instead of waiting to accumulate enough money to buy jewellery or coins, investors can gradually build their gold holdings over time.
From Investment to Jewellery
While digital gold is often viewed as a substitute for physical ownership, Luniya believes it actually complements traditional buying habits.
He explained that investors can accumulate gold digitally over several years and eventually convert those holdings into jewellery whenever required, particularly for weddings or family occasions.
A key innovation enabling this transition is the Electronic Gold Receipt (EGR), an exchange-traded instrument backed by physical gold stored in regulated vaults. According to Luniya, EGRs could eventually allow investors to transfer gold directly from their demat account to a jeweller, paying only the making charges or any additional quantity required.
“This makes gold accumulation far more efficient while still allowing families to eventually own physical jewellery,” he said.
Trust Through Standardisation
Luniya also highlighted the impact of mandatory hallmarking in improving consumer confidence.
Earlier, buyers often had little certainty about the purity of jewellery, with many discovering years later that ornaments sold as 22-carat gold were of lower quality. Today, BIS hallmarking and digital verification have standardised quality, making transactions significantly more transparent.
He believes this increased trust provides the foundation for wider adoption of digital gold ownership.
Unlocking a Sleeping Asset
According to Luniya, India’s privately held gold is effectively a “sleeping asset.”
While households continue buying gold every year, the country also imports hundreds of tonnes annually, placing pressure on foreign exchange reserves.
“If even a small portion of the gold already lying in Indian homes becomes financially productive, it can release enormous liquidity into the economy,” he said.
That liquidity, he argued, could support businesses, improve access to credit and reduce dependence on fresh imports.
Rather than encouraging people to stop buying gold, Luniya advocates changing how it is accumulated and utilised.
Lessons From History
During the discussion, Luniya referred to historical examples to underline gold’s strategic importance.
He cited the United States’ gold policies during the Great Depression and India’s decision to pledge gold reserves during the 1991 balance-of-payments crisis as examples of how gold has served as a critical financial asset during periods of economic stress.
His broader point was that gold should not merely remain locked away but should be capable of supporting economic activity whenever required.
Why Gold Remains Relevant
The conversation also touched upon the resurgence of gold globally.
Luniya noted that central banks across the world have increased their gold purchases amid geopolitical tensions, rising sovereign debt and efforts to diversify reserves beyond the US dollar.
Against this backdrop, he believes India’s own household gold reserves can play a far greater role in strengthening the country’s financial resilience.
Among the various investment avenues available today—including Gold ETFs, digital gold and other market-linked products—he identified Electronic Gold Receipts as one of the most promising developments because they combine the security of physical gold with the convenience of electronic ownership.
The Road Ahead
Luniya believes younger investors are already leading the shift towards digital assets.
Unlike previous generations, who primarily associated gold with jewellery, today’s investors are increasingly comfortable owning financial assets electronically while retaining the flexibility to convert them into physical form whenever required.
For him, the future of gold lies not in replacing tradition but in modernising it.
Families will continue buying jewellery for emotional and cultural reasons, but the process of saving and investing in gold is likely to become increasingly digital. If that transition gathers pace, Luniya believes India’s vast household gold reserves could evolve from being a passive store of wealth into a productive financial asset—one that benefits not only individual investors but the broader economy as well.
-
 News4 weeks ago
SC Says No Stay On New UPI Charges Above ₹2,000
-
 Podcast1 year ago
Nitin Jain: From IIT to Investment Titan, Managing ₹60,000 Crore AUM
-
 News1 month ago
NSE Makes Long-Awaited Market Debut After ₹22,562-Crore IPO
-
 Explainer5 months ago
How Much SIP Do You Need to Build ₹1 Crore? The Power of Time and Compounding
-
 Podcast2 years ago
From ₹1 Lakh Lost to Managing ₹650 Crore: How Divam Sharma of Green Portfolio Built a Fundamental Investing Approach
-
 Podcast4 months ago
Can ₹200 SIPs Create India’s Next Investing Revolution? Ravi Kumar Jha’s Big Bet On Financial Inclusion
-
 Podcast1 year ago
From ₹1 Lakh Lost to Managing ₹650 Crore: How Divam Sharma of Green Portfolio Built a Fundamental Investing Approach
-
 News2 weeks ago
UPI Charges on Payments Above ₹2,000 Delayed Until After Diwali