News
Gold Is Falling: Should You Be Worried About Your Investment?
Gold has spent much of the year making headlines for all the right reasons – prices climbed sharply and investors watched their gold holdings become more valuable.
Now, the mood has changed.
After hitting a recent high of around ₹1.63 lakh per 10 grams on August 24, MCX gold fell to around ₹1.52 lakh per 10 grams in early September. That is a sizable fall in a short period, and for someone who bought gold near its recent highs, it can be uncomfortable.
But before you start wondering whether it is time to sell your gold, there is a more important question to ask: Is a 10–15% correction in gold actually unusual?
Gold can fall too – and history proves it.
Gold often gets a reputation as the “safe” investment. But safety does not mean that its price can never fall.
A correction simply means that an asset has fallen from a recent peak. If gold rises to ₹1 lakh and then drops to ₹87,000, that is a 13% drawdown.
And historically, corrections of this size have happened quite regularly.
Data going back to 1980 shows that gold’s average intra-year drawdown has been around 13%. Gold has seen corrections of roughly 10–15% in several years, including 1984, 1985, 1993, 2004, 2007, 2009, 2020, 2021, 2022 and 2023.
In other words, a double-digit fall in gold isn’t necessarily a sign that something has gone terribly wrong.
In fact, gold has experienced much steeper falls in the past. The drawdown was around 40% in 1980, 25% in 1981 and 23% in both 1982 and 1983. During the global financial crisis, gold fell about 20% within the year, while the 2013 correction was around 24%.
So, if you own gold and are watching a 10% or 15% correction today, history suggests that this is not unprecedented.
But here’s the part investors should remember
A correction doesn’t automatically mean gold is a bad investment. One of the most interesting findings from the historical data is that gold often recovered after experiencing sizable falls during the year.
According to the FundsIndia analysis cited by Moneycontrol, gold ended the calendar year with a positive return in 78% of the years despite experiencing an intra-year drawdown.
For example, gold fell as much as 20% during 2008 but still ended the year with a 29% return. In 2020, gold saw a maximum drawdown of around 15%, yet finished the year up 28%. In 2023, it corrected by around 10% during the year but still ended with a 15% gain.
The lesson isn’t that gold will definitely bounce back every time. It won’t.
The lesson is that a temporary fall and a bad long-term investment are not necessarily the same thing.
So, what should you do if you own gold?
This is where the conversation becomes personal finance rather than just market commentary.
If you bought gold as part of a diversified portfolio and your investment horizon is several years, a short-term correction shouldn’t automatically change your plan.
Think about why you bought gold in the first place.
Was it to make a quick return? Was it for diversification? Are you saving for a long-term goal? Are you holding physical gold for a future wedding or another planned expense?
Your answer matters more than the price movement of the last few days.
If gold is only one part of a diversified portfolio, a correction could simply be a reminder that every asset class has its ups and downs.
Don’t confuse a correction with a sale signal
One common mistake investors make is buying an asset after it has already rallied sharply because everyone around them is talking about it – and then selling when the price falls.
That’s essentially buying high and selling low. The recent gold movement is a good reminder that even an asset widely considered a hedge or store of value can be volatile. Instead of asking, “Gold has fallen. Should I sell?”, ask:
“Has anything changed about why I own gold?”
If the answer is no, a temporary correction may not require a dramatic change in your financial plan.
On the other hand, if you bought gold purely because prices were rising and expected them to keep rising, the correction is a useful reminder to revisit that strategy.
Should you buy more because gold has fallen?
Not necessarily. A fall in price doesn’t automatically make an asset cheap.
Gold could fall further, recover quickly, or move sideways for months. Historical data can tell us that corrections have happened before, but it cannot tell us exactly where gold prices will go next.
So, rather than trying to guess the exact bottom, investors should focus on asset allocation, investment horizon and financial goals.
If you are building a portfolio, gold can have a role as a diversification asset. But that doesn’t mean your portfolio should be built around gold simply because it has recently delivered strong returns.
The bigger money lesson
The biggest takeaway from gold’s current correction isn’t about gold at all.
It’s about how we react to volatility. When an investment is going up, it is easy to believe that the rise will continue forever. When it falls, it is equally easy to assume that the worst is yet to come.
Neither assumption is particularly useful. Gold has had several double-digit corrections over the decades. Yet, historically, those falls haven’t always prevented it from ending the year with positive returns.
So if you’re looking at your gold investment today, don’t just look at the red number on your screen. Look at why you bought it, how much of your portfolio it represents, and when you actually need the money.
Because when it comes to personal finance, the goal isn’t to predict every rise and fall.The goal is to build a financial plan that doesn’t fall apart every time the market does.
Source: MoneyControl
India’s consumer sector is heading into the festive season with demand holding up, but rising input costs are putting pressure on company margins.
Consumer companies are seeing steady demand across categories, with rural consumption also showing signs of resilience. However, higher costs of key raw materials could make it harder for companies to protect their profits.
What’s pushing costs up?
Several FMCG companies have flagged rising input costs during the September quarter.
Higher prices of commodities and raw materials, along with elevated crude oil prices, are adding to the cost of making and transporting everyday products. Packaging costs can also rise when crude-linked inputs become more expensive.
Companies are trying to manage the pressure through cost efficiencies, supply-chain measures and selective price increases.
Will consumers pay more?
That’s the key question.
When input costs rise, companies have three broad choices: absorb the additional cost and take a hit to margins, cut costs elsewhere, or pass some of the increase on to consumers.
If cost pressures persist, price hikes across everyday products could eventually follow.
For consumers, that could mean paying a little more for everything from packaged food and personal-care products to household essentials.
Festive demand could offer some relief
The good news for FMCG companies is that festive spending could provide a boost.
With Diwali falling later this year, some festive demand is expected to shift into the December quarter rather than showing up fully in the September quarter. Categories such as snacks, sweets, gifting and other consumer products could see stronger demand as the festive season progresses.
Rural demand remains important
Rural consumption will also be closely watched. Smaller towns and rural markets are an important growth driver for FMCG companies, and a recovery in rural spending could support volumes.
But uneven weather conditions and pressure on agricultural incomes remain concerns.
What Happens If Costs Stay High?
For now, demand remains relatively strong. But if input costs continue to stay elevated, companies may eventually pass some of that pressure on to consumers.
There was a time when buying a designer bag was fairly straightforward: you liked it, you could afford it, and you bought it.
Now, things are a little different.
People are booking appointments, joining waitlists and hunting down specific colours, materials and limited-edition pieces. There are collectors with entire rooms dedicated to their handbags. And increasingly, buyers aren’t looking at these bags only as fashion purchases; they are looking at what the bag could be worth years down the line.
That got me thinking: when did a handbag start looking like an investment?
The Numbers Are Making The Case
According to the Knight Frank Luxury Investment Index, handbags were the best-performing luxury collectible category in 2024, gaining 2.8%.
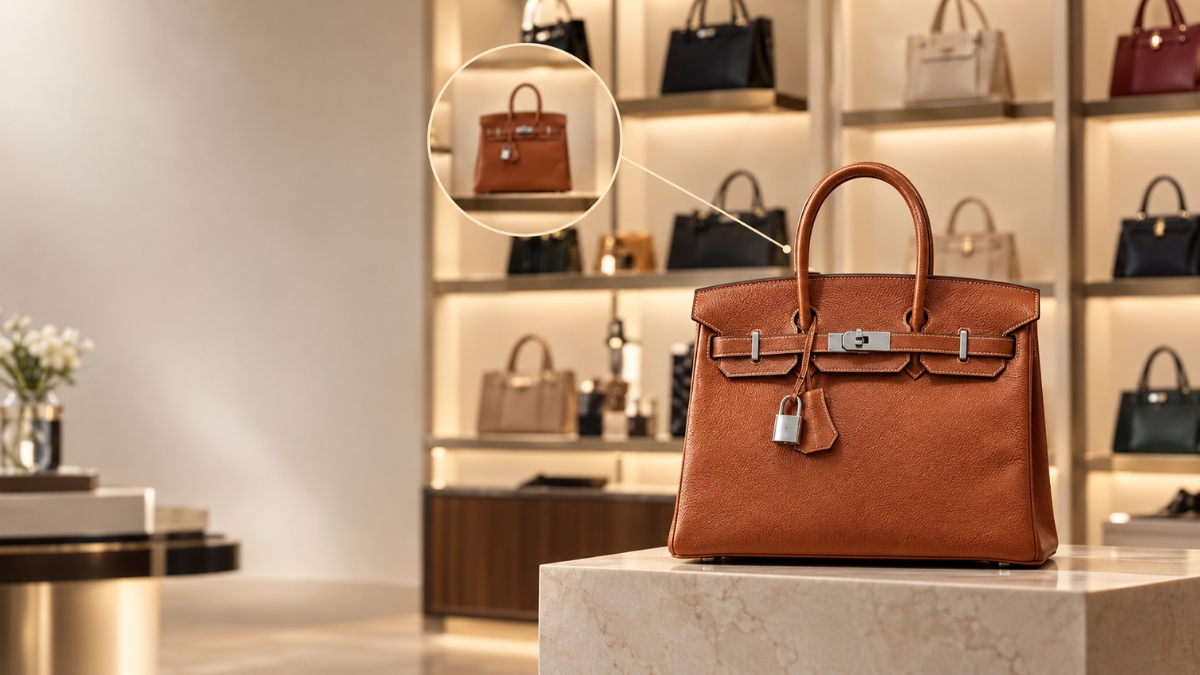
Economic Times also highlighted how certain luxury handbags can sell for significantly more in the resale market than their original retail price. One example cited was an Hermès Birkin 25, which retailed at around ₹10.2 lakh but was selling for roughly ₹18 lakh in the resale market.
That’s a pretty interesting premium for something that is technically still a handbag.
Forbes has been making a similar argument for years. Its research has looked at designer handbags particularly sought-after Hermès pieces as an alternative investment, comparing their appreciation with traditional luxury assets such as art.
Of course, that doesn’t mean your wardrobe is suddenly a stock portfolio. But it does show that something interesting is happening in the luxury market.
Scarcity Is Doing A Lot Of The work
The most valuable handbags aren’t necessarily the most expensive ones. They’re often the ones people can’t easily get.
Limited production, discontinued designs, rare colours and materials, celebrity associations and strong brand demand can all contribute to resale value.
And that explains the waitlists.
The scarcity itself becomes part of the product. If everyone could walk into a store tomorrow and buy the same bag, some of that exclusivity and potentially some of its resale appeal would disappear.
It’s the same basic idea we see with many collectibles: when supply is limited and demand stays strong, people are willing to pay more.
This Is Also Creating A New Kind Of Collector
There are serious collectors building entire portfolios of handbags. Some buy specific models because they believe they will hold their value. Others look for pieces that are rare or difficult to find.
And yes, there are people whose collections are large enough to require dedicated storage.
At that point, we’re moving beyond fashion. We’re talking about an asset that someone is deliberately acquiring, preserving and potentially reselling.
And Then There’s The Collateral Angle
Here’s where things get even more interesting.
In some markets, specialist lenders allow owners to borrow against valuable luxury handbags, using them as collateral. In simple terms, the bag is valued and the owner can potentially access a loan against that value.
But this is where one should draw the line between “valuable asset” and “investment.”
Not every designer bag will qualify. And not every bag will be appreciated. Brand, model, condition, authenticity, rarity and resale demand can all influence its value.
So, are designer bags actually investments?
Sometimes. But not every expensive handbag is an investment. A stock can generate dividends. A bond can generate interest. A property can generate rent. A handbag doesn’t do any of that.
Its investment potential comes from what someone else may be willing to pay for it later. And that makes the market much more dependent on trends, scarcity and consumer demand.
So yes, a ten lakh handbag could potentially become more valuable over time.
But that doesn’t mean spending ten lakh on a handbag is automatically a smart financial decision. The smarter way to look at it may be this: a designer bag can be a luxury purchase that happens to have investment potential, not an investment that happens to be a bag.
Gold has had a pretty dramatic year.
After hitting record highs earlier in 2026, gold prices have now corrected by more than 23%. International prices fell from around $5,419 an ounce in January to just above $4,155 by October 5. In India, MCX gold also slipped from its yearly high of ₹2.48 lakh per 10 grams to around ₹1.49 lakh.
With Diwali and the wedding season around the corner, the big question for buyers is simple: Is this dip a good opportunity to buy gold?
Why has gold fallen?
The recent correction has been driven by a mix of global factors.
Higher US Treasury yields and a stronger US dollar have put pressure on gold prices. Changing expectations around global interest rates and geopolitical developments have also contributed to the decline.
But a fall in price doesn’t automatically mean gold is now “cheap”.
Kaveri More, Commodity Technical Analyst at Choice Broking, says the correction looks more like a period of consolidation and repricing rather than a signal to rush in and buy everything at once.
So, should you buy before Diwali?
If you are buying gold for Diwali, Dhanteras or an upcoming wedding, your approach can be different from someone buying purely as an investment.
For jewellery, buying according to your actual requirement may make sense rather than trying to predict where prices will bottom.
For investment purposes, experts suggest avoiding a lump-sum purchase right now. Instead, investors could consider staggering their purchases across 3–4 tranches over the coming weeks.
The idea is simple: you don’t have to perfectly time the lowest gold price.
For investors who don’t specifically need physical gold, Gold ETFs can also be considered. They provide exposure to gold without the making charges associated with jewellery.
What about jewellery buyers?
The festive season could still bring some demand, but consumers are becoming more careful about how much they spend.
Colin Shah, Managing Director of Kama Jewellery, expects festive and wedding demand to see occasional spikes of around 15–20% during the peak season. However, buyers are increasingly looking at lightweight and contemporary jewellery that fits within their budgets.
The average ticket size is expected to be around ₹1.5 lakh–₹3 lakh.
A 23% correction may make gold look more attractive, but a lower price doesn’t mean the bottom is here.
If you need jewellery for a genuine occasion, buy according to your requirement and budget.
If you’re buying gold as an investment, don’t put all your money in at once. Staggering purchases can help reduce the risk of getting your timing wrong.
And most importantly, don’t use money meant for short-term expenses just because gold prices have fallen.
Source: MoneyControl
-
 Podcast1 year ago
Nitin Jain: From IIT to Investment Titan, Managing ₹60,000 Crore AUM
-
 Explainer4 months ago
How Much SIP Do You Need to Build ₹1 Crore? The Power of Time and Compounding
-
 News2 weeks ago
NSE Makes Long-Awaited Market Debut After ₹22,562-Crore IPO
-
 Podcast1 year ago
From ₹1 Lakh Lost to Managing ₹650 Crore: How Divam Sharma of Green Portfolio Built a Fundamental Investing Approach
-
 Podcast4 months ago
Can ₹200 SIPs Create India’s Next Investing Revolution? Ravi Kumar Jha’s Big Bet On Financial Inclusion
-
 News1 week ago
SC Says No Stay On New UPI Charges Above ₹2,000
-
 Podcast1 year ago
From ₹1 Lakh Lost to Managing ₹650 Crore: How Divam Sharma of Green Portfolio Built a Fundamental Investing Approach
-
 News2 weeks ago
Will Your Phone’s Tempered Glass Get More Expensive From 2027?