Markets
NSE Changes Pre-Open Market Rules From September 7: What Traders Need to Know
The revised 9 am to 9:15 am session changes order-entry windows and gives greater focus to price-time priority during matching The National Stock Exchange (NSE) has introduced revised rules for its pre-open auction session from September 7, changing how orders are entered, modified, cancelled and matched before regular trading begins. The overall pre-open session remains unchanged at 9:00 am to 9:15 am. However, the 15-minute window is now divided into specific stages for order entry, limit-order activity, order matching and the transition to normal trading. The revised system applies to stocks in the equity cash market, including SME securities, InvITs and REITs, as well as the derivatives segment.
First Five Minutes Become Important
Under the revised system, the first order-entry period runs from 9:00 am to 9:05 am.
During this five-minute window, market participants can place both market and limit orders. They can also modify or cancel these orders.
Earlier, the order-entry period ran from 9:00 am to 9:08 am, allowing these activities throughout the eight-minute window.
The shorter initial window means traders may need to act earlier, particularly when markets are responding to major overnight developments, sharp global moves or significant company-specific news.
Limit Orders Get a Separate Window
The second phase runs from 9:05 am to 9:10 am.
During this period, fresh limit orders can be entered, while existing limit orders can also be modified or cancelled. However, market orders cannot be modified or cancelled during this window.
The system may also randomly stop the order-entry period during the final two minutes of the scheduled window.
Under the earlier system, order entry, modification and cancellation activities were permitted from 9:00 am to 9:08 am without the same separation between market and limit orders.
Order Matching From 9:10 am
The third phase, from 9:10 am to 9:12 am, is dedicated to order matching and trade confirmation.
No fresh orders can be entered, modified or cancelled during this period. The opening price for a stock is determined through the equilibrium price mechanism.
Market buy and sell orders are first matched against each other based on time priority at the equilibrium price.
Any eligible market orders left unmatched are then matched with limit orders based on price-time priority. Remaining limit orders are subsequently matched with other limit orders using the same price-time priority principle.
This gives importance to both the price of an order and the time at which it was placed.
Buffer Period Remains Unchanged
The final three minutes, from 9:12 am to 9:15 am, continue to serve as the buffer period.
This period allows the market to transition from the pre-open auction to the regular continuous trading session.
There is no change to this part of the market-opening process.
How Is the Opening Price Decided?
The opening price is determined through the demand-supply mechanism, known as the equilibrium price.
The equilibrium price is the level at which the maximum volume of orders can be executed.
If more than one price allows the same maximum executable volume, the price with the minimum order imbalance is considered.
If multiple prices still meet these conditions, the price closest to the previous trading day’s closing price is selected as the equilibrium price.
What Does the Change Mean for Traders?
The revised structure makes the pre-open process more segmented and places greater emphasis on when and at what price orders are entered.
For traders, the biggest change is the reduction of the initial order-entry period from eight minutes to five minutes. Market orders also receive different treatment after 9:05 am, as they cannot be modified or cancelled during the second phase.
The revised matching process could make price-time priority more important in determining which eligible orders are executed.
Overall, the NSE’s revised pre-open auction is aimed at making opening price discovery more structured while reducing last-minute market-order activity before regular trading begins.

Shares of the National Stock Exchange (NSE) have fallen below their initial public offering (IPO) price less than two weeks after making their stock market debut. The decline has erased all the gains made on listing day and reduced the exchange’s market value by nearly Rs 41,000 crore from its peak, according to the source.
NSE shares fall below IPO price
NSE shares were listed on the BSE on September 24 at Rs 1,800 per share, compared with the IPO price of Rs 1,785.
The stock initially attracted strong buying interest. It rose more than 5% during the first hour of trading and touched an intraday high of Rs 1,878.
At that level, NSE’s market capitalisation reached around Rs 4.64 lakh crore.
However, the initial momentum did not last.
The stock subsequently came under selling pressure and fell to Rs 1,712, its lowest level since listing. This was around 9% below its listing-day high and about 4% below its IPO price.
NSE slips out of India’s top 10 most valuable companies
The fall in the share price has also affected NSE’s position among India’s most valuable listed companies.
Its market capitalisation dropped to around Rs 4.27 lakh crore, pushing the exchange out of the top 10 and down to the 12th position.
NSE now trails several major listed companies, including Reliance Industries, Bharti Airtel, HDFC Bank, ICICI Bank, State Bank of India, TCS, Bajaj Finance, Larsen & Toubro, LIC, Hindustan Unilever and Sun Pharma.
NSE stock recovers slightly
The stock recovered some ground on Tuesday, rising 1.53%, or Rs 26.35, to Rs 1,749.85.
The recovery came as India’s broader equity markets also moved higher.
The Sensex gained 685.34 points, or 0.95%, to close at 73,067.81, while the Nifty rose 220.35 points, or 0.98%, to settle at 22,776.10.
Investors bought shares in sectors including pharmaceuticals, private banks and oil and gas ahead of the outcome of the Reserve Bank of India’s policy meeting.
What does the fall mean for NSE investors?
The NSE’s movement shows how quickly a newly listed stock can move after its debut.
The exchange initially gained nearly 5% from its IPO price to reach Rs 1,878 before falling below the Rs 1,785 issue price.
For investors who bought the stock after listing, the current price therefore represents a decline from both the listing-day high and the IPO price.
However, the share price can continue to change with market conditions, investor sentiment and company-specific factors.
The Simple Hai! does not hold any responsibility for investment decisions or financial losses based on this article. This content is for informational and educational purposes only and should not be considered investment advice. Investors should conduct their own research and consult a SEBI-registered investment adviser before making any investment decisions.
The Securities and Exchange Board of India (SEBI) is examining position limits for non-agricultural commodity contracts as it looks to improve liquidity and market depth without weakening risk controls.
SEBI Chairman Tuhin Kanta Pandey said the regulator is also working on several other issues that could make India’s commodity derivatives market more efficient.
What are position limits?
Position limits restrict how large a position a market participant can hold in a particular commodity contract. Such limits are designed to prevent excessive concentration and reduce the risk of market manipulation. However, limits that are too restrictive can also make it harder for contracts to attract enough participants and trading activity.
SEBI is therefore examining whether the existing limits for non-agricultural contracts can be adjusted to help these markets gain greater depth. Pandey said the objective is to allow contracts to grow while maintaining appropriate risk controls.
SEBI looks at physical settlement rules
SEBI is also examining how commodity contracts are settled.
Pandey said that in some agricultural commodities, requiring physical settlement from the beginning can make it harder for a contract to develop.
A phased approach could allow contracts to mature before physical settlement becomes mandatory, he said.
SEBI has completed consultations on the issue and guidelines are expected to follow.
GST issues also under discussion
The regulator is engaging with stakeholders on GST-related issues affecting participants who give or receive commodities through exchange platforms.
The aim is to reduce structural friction that can make participation in commodity markets more difficult.
SEBI’s broader focus is on creating markets that can attract producers, commercial users, processors, farmers and other participants while maintaining market integrity.
Why does commodity-market liquidity matter?
A deeper market generally means more buyers and sellers are available to trade.
For businesses that use commodities as part of their operations, a liquid derivatives market can help them manage price risks. This includes physical hedgers who use contracts to protect themselves against changes in commodity prices.
Pandey said technology can improve access and efficiency, but technology used in commodity markets must reflect the needs of producers, farmers, processors, commercial users and physical hedgers.
SEBI wants more investor awareness
SEBI also plans to strengthen investor awareness through Project Jagrook.
The initiative will focus on educating farmers, farmer producer organisations (FPOs), MSMEs, hedgers and other users about commodity derivatives.
Pandey stressed that greater access to financial markets is not enough if participants do not understand how the products work.
For smaller businesses and farmers, this is particularly important because commodity derivatives can help manage price risk but also carry risks that participants need to understand.
More participation in cash and derivatives markets
SEBI is also working towards deeper and more liquid cash markets.
According to Pandey, wider participation, stronger securities borrowing and lending and more efficient hedging and arbitrage could improve price discovery.
Better interaction between cash and derivatives markets could also help market participants manage risks more efficiently.
However, SEBI has stressed that simpler regulation should not mean weaker compliance.
Controls around client funds, margins, reporting and supervision will remain important, with market trust and integrity continuing to be key priorities.
Foreign investors get a role in commodity derivatives.
The developments follow a recent SEBI board decision to allow foreign portfolio investors (FPIs) to participate in physically settled, non-agricultural commodity derivative contracts, subject to safeguards.
The move could bring wider participation to India’s commodity derivatives market.
For the common investor and businesses, SEBI’s latest approach is aimed at balancing two objectives: making commodity markets deeper and easier to use while ensuring that stronger participation does not come at the cost of market safety and investor protection.
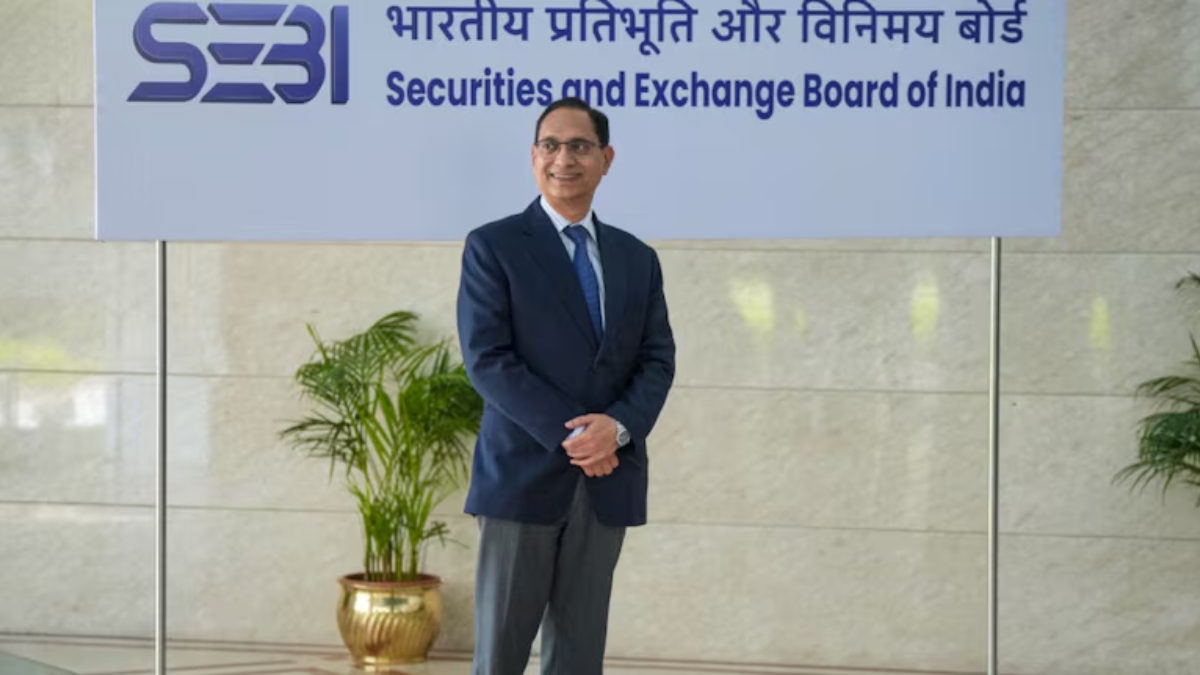
The question of how much Indian money can move overseas is a matter for the Reserve Bank of India (RBI), not the Securities and Exchange Board of India (SEBI), SEBI Chairman Tuhin Kanta Pandey said on Wednesday. His comments came days after SEBI’s board approved new regulations allowing portfolio managers to invest client funds in specified overseas securities. Speaking at the annual conference of the Association of Portfolio Managers in India (APMI), Pandey was asked whether the new permission could result in more Indian money moving abroad. He said the amount that can move overseas and the route through which it can be sent must follow the Liberalised Remittance Scheme (LRS) and the Foreign Exchange Management Act (FEMA) rules.
What has SEBI changed?
SEBI’s board approved the SEBI (Portfolio Managers) Regulations, 2026 on September 24.
The new regulations allow discretionary and non-discretionary portfolio managers to invest in specified overseas securities.
These include:
- – Listed equity and debt
- – Real Estate Investment Trusts (REITs)
- – Overseas mutual funds
- – Exchange-traded funds (ETFs)
- – Index funds
- – Foreign government debt
However, the permission remains subject to FEMA and RBI’s LRS framework.
This distinction is important. SEBI’s permission allows portfolio managers to make certain overseas investments, but it does not independently determine how much money can leave India.
Pandey did not specify how the limits would apply to overseas allocations by PMS clients and referred that question to the RBI.
Why does this matter to Indian investors?
For investors using portfolio management services (PMS), the regulatory change could provide access to a wider range of overseas investments.
But the ability to invest abroad does not mean investors can freely transfer unlimited amounts of money overseas.
The applicable limits and foreign exchange rules continue to matter. The Moneycontrol report notes that overseas investments under the new PMS framework remain subject to the RBI’s LRS and FEMA requirements.
For an ordinary investor, the key point is that SEBI regulates the investment product and intermediary, while RBI’s foreign exchange framework determines the applicable limits for money moving overseas.
SEBI and RBI working on faster FPI registration
Pandey also said SEBI and the RBI are working to make registration for Foreign Portfolio Investors (FPIs) faster and more digital.
The RBI is looking at allowing FPI registration documents to be uploaded through SWIFT, according to Pandey.
SEBI has already introduced several measures aimed at simplifying the process, including:
- A revamped NSDL front end
- India Market Access portal
- A common application portal with tracking
- Digital signatures instead of physical signatures
- E-power of attorney
Pandey said these measures can reduce the need for processes such as notarisation, apostille and consularisation.
What about India’s market performance?
Pandey was also asked about the recent decline in the Indian market compared with markets in Japan and South Korea.
He said decisions about where investors should put their money are for investors to make and that it would not be appropriate for regulators to comment on such investment choices.
He instead pointed to the regulators’ focus on making FPI registration easier.
SEBI also flags issue of inactive listed companies
Pandey also addressed concerns about listed companies that have little or no visible business activity.
He said stock exchanges have a continuing responsibility to monitor companies after listing. Where a company is not physically present or carrying out economic activity, delisting provisions are available.
He also said physical verification by exchanges is feasible and stressed that the process should be followed properly so investors can have confidence that listed companies are genuine.
The common investor takeaway
The latest change does not mean SEBI has opened an unrestricted route for Indian money to move overseas.
SEBI has allowed portfolio managers to invest in specified foreign securities, but those investments remain subject to the RBI’s foreign exchange framework and FEMA rules.
So, for investors, the important distinction is simple: SEBI decides what regulated portfolio managers can invest in, while the RBI’s rules govern the broader framework for moving money abroad.
Source: Moneycontrol
-
 News4 weeks ago
SC Says No Stay On New UPI Charges Above ₹2,000
-
 Podcast1 year ago
Nitin Jain: From IIT to Investment Titan, Managing ₹60,000 Crore AUM
-
 News1 month ago
NSE Makes Long-Awaited Market Debut After ₹22,562-Crore IPO
-
 Explainer5 months ago
How Much SIP Do You Need to Build ₹1 Crore? The Power of Time and Compounding
-
 Podcast2 years ago
From ₹1 Lakh Lost to Managing ₹650 Crore: How Divam Sharma of Green Portfolio Built a Fundamental Investing Approach
-
 Podcast4 months ago
Can ₹200 SIPs Create India’s Next Investing Revolution? Ravi Kumar Jha’s Big Bet On Financial Inclusion
-
 Podcast1 year ago
From ₹1 Lakh Lost to Managing ₹650 Crore: How Divam Sharma of Green Portfolio Built a Fundamental Investing Approach
-
 News2 weeks ago
UPI Charges on Payments Above ₹2,000 Delayed Until After Diwali